General Contractor Insurance in North Carolina: Requirements, Subcontractors and Builder's Risk
For licensed general contractors and builders running residential and commercial projects across North Carolina.
For licensed general contractors and builders running residential and commercial projects across North Carolina.
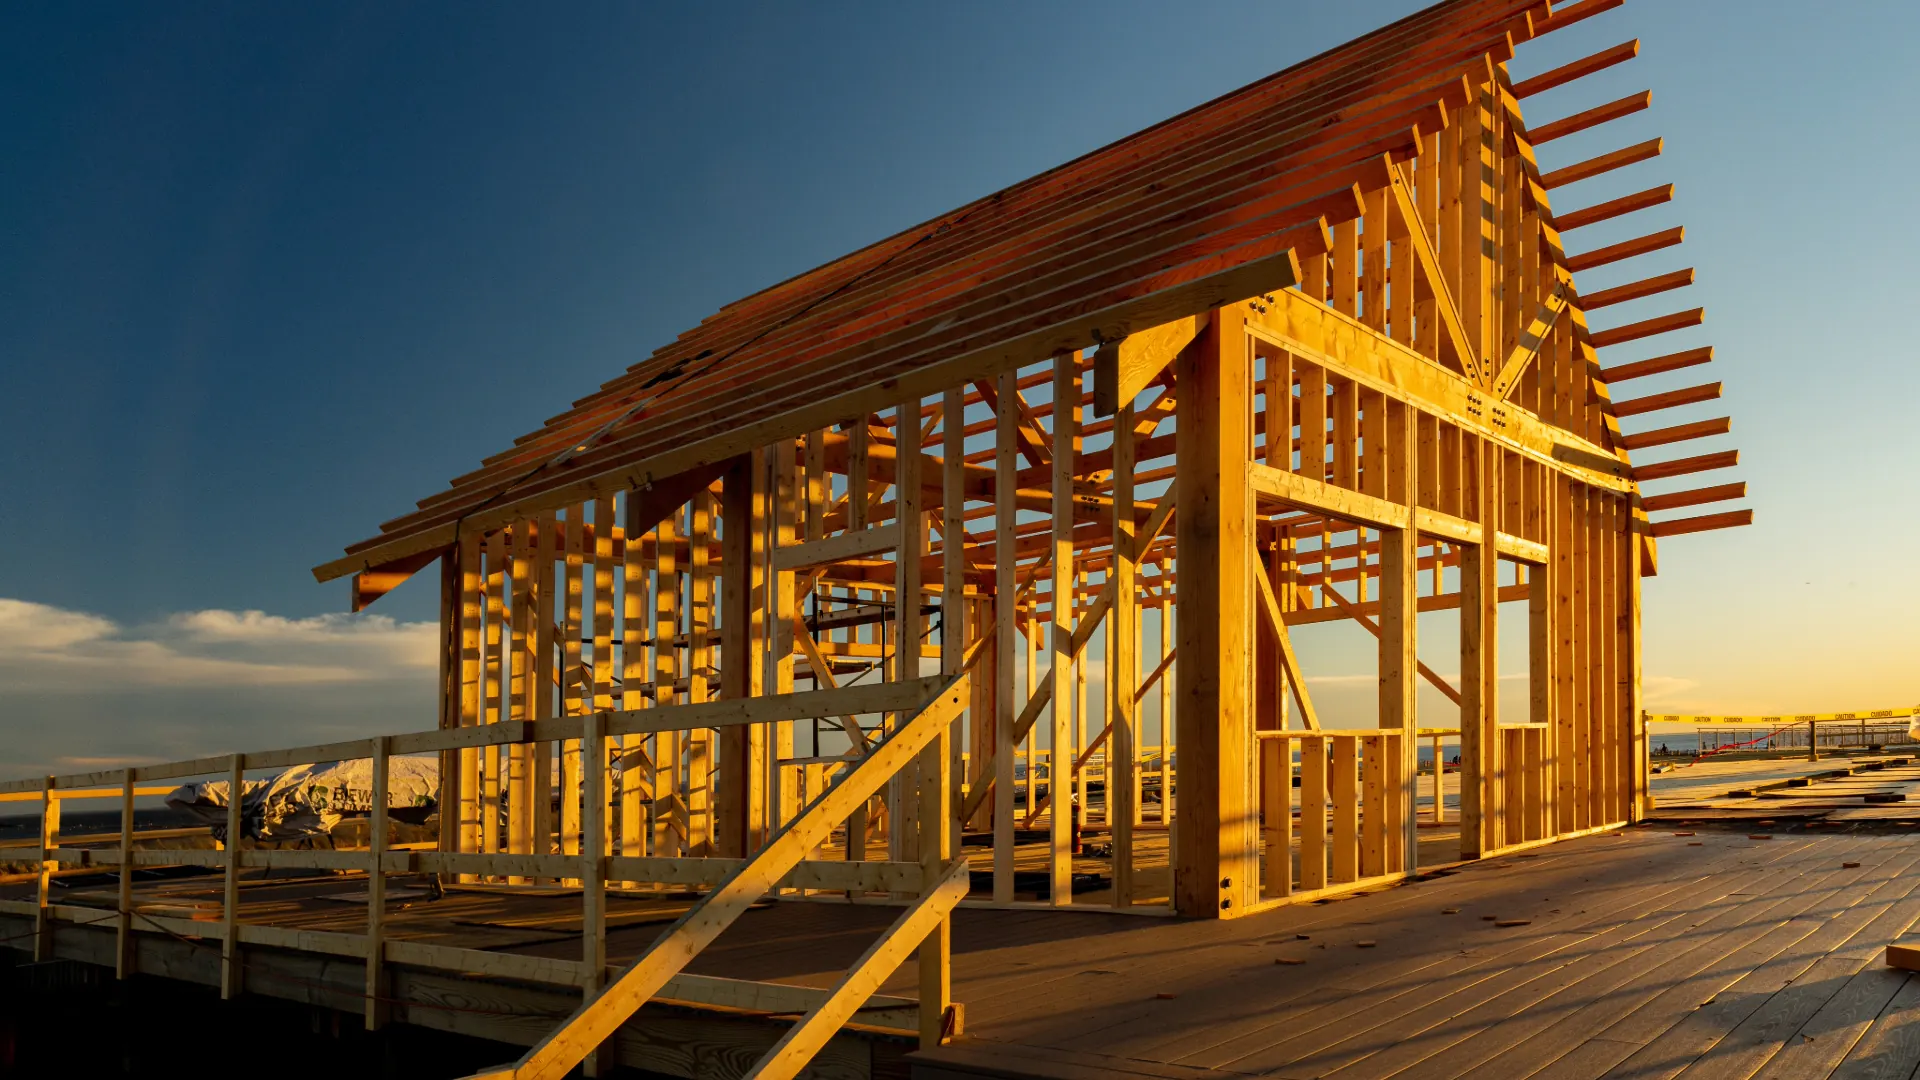
A general contractor's insurance has to cover more than the GC's own crew. It has to answer for every subcontractor on the job, the project itself while it is being built, and claims that arrive years after the certificate of occupancy.
North Carolina licensing asks for proof of finances, not liability insurance. The insurance requirements come from workers comp law, building permits, owners, lenders and the contracts you sign, and the biggest surprise for most GCs is the bill for uninsured subcontractors at audit.
General liability with completed operations. Covers injuries and property damage from your operations and your subs' work, including claims after the project is finished. Watch for residential, condo and tract-home exclusions.
Workers compensation. Covers your employees and, if you do not collect certificates, can end up paying for your subcontractors' employees too.
Builder's risk. Covers the building under construction, materials on site and often materials in transit, from fire, theft, vandalism and storms. On the coast, confirm that named storm is covered and what the deductible is. See what builder's risk covers and who buys it.
Contractor's equipment and inland marine. Covers owned and rented equipment and tools.
Commercial auto. Covers trucks, trailers and employees driving for the business.
Umbrella or excess liability. Adds limits most owners, lenders and public projects require.
Performance and payment bonds. Guarantee to the owner that the project will be finished and subs and suppliers paid. Bonding capacity depends on your financial statements, not your insurance.
Professional liability. Needed for design-build and construction management work, where general liability excludes design errors.
Wrap-up programs (OCIP and CCIP). On large projects, the owner (OCIP) or the GC (CCIP) buys one liability and workers comp program for everyone on site. Your own policy must coordinate with it, especially for completed operations.
Forms, endorsements and availability vary by insurance company. Your own policy and your contracts govern.
When you need a license. A general contractor license is required when the cost of the project is $40,000 or more (G.S. 87-1, NCLBGC). Owner-builders building their own home to live in are exempt under conditions in the statute.
License tiers. The license limitation sets the largest single project you can take: Limited up to $750,000, Intermediate up to $1,500,000, and Unlimited with no cap (G.S. 87-10). Each tier must show working capital, net worth or a surety bond under the Board's rules (NCLBGC Laws and Rules).
No liability insurance requirement for licensing. Neither the statute nor the Board's rules require general liability insurance to hold a GC license. Owners, lenders, local governments and contracts usually do.
Workers comp at permits. Building permit applicants for work of $40,000 or more must show proof of workers comp coverage as required by law (G.S. 87-14). Employers with three or more employees must carry it (G.S. 97-2).
Subcontractor certificates. A contractor who hires a subcontractor without first getting a certificate of workers comp coverage can be liable for the sub's injured workers, even if the sub has fewer than three employees (G.S. 97-19). Get the certificate before the sub starts, and keep it in the job file.
Penalties. Failing to carry required workers comp brings a daily civil penalty and possible criminal charges, and responsible officers can be held personally liable (G.S. 97-94).
Vehicles. Business vehicles need at least North Carolina's 50/100/50 liability minimums on policies issued or renewed on or after July 1, 2025 (NCDOI).
General contractor pricing follows the work you run and how you manage your subs. The main factors:
We do not publish average prices. A licensed advisor quotes your actual operation across more than 100 insurance companies.
The state requires workers comp at three or more employees and proof of it for building permits of $40,000 or more. Liability limits, builder's risk and bonds come from owners, lenders and contracts.
Yes, when the project costs $40,000 or more. Below that, no general contractor license is required, though trade work still needs trade licenses.
Limited allows single projects up to $750,000, Intermediate up to $1,500,000, and Unlimited has no project limit.
No. The license requires proof of financial standing, not liability insurance, but nearly every owner and lender will require it.
If you did not get a certificate before the sub started, you can be liable for the sub's injured workers, and your own workers comp audit will usually charge for that sub's payroll.
Whoever the contract says. Many residential contracts put it on the builder, while many commercial owners buy it themselves; it must be clear before the project starts.
A single liability and workers comp program that covers the owner, the GC and the subs on one project. It is called an OCIP when the owner buys it and a CCIP when the contractor buys it.
Yes. Owners can sue the general contractor for anything that goes wrong on the project, and contracts will require you to carry it.
Forms, endorsements, and availability vary by insurance company. Your own policy governs.
Sizemore Insurance is an independent insurance company founded in North Carolina in 1977. Tell us what your business does and what you need to protect, and a licensed advisor will compare more than 100 insurance companies to find the coverage that fits. Insurance made just for you.
Sources: G.S. 87-1, who is a general contractor ($40,000 threshold); G.S. 87-10, license classifications and limitations; NCLBGC 2026 Laws and Rules (21 NCAC 12A .0204, financial requirements); G.S. 87-14, building permits and workers compensation proof; G.S. 97-2, workers compensation definitions (3 or more employees); G.S. 97-19, contractor liability and subcontractor certificates; G.S. 97-94, penalties for not carrying workers compensation; NC Licensing Board for General Contractors; NC Department of Insurance, auto changes effective July 1, 2025.
Forms, exclusions, endorsements, and availability vary by carrier. This page is general information, not a policy or legal advice. Review your own policy or talk to your advisor.