Handyman Insurance in North Carolina: Coverage and How Much You Can Do Without a License
For handymen and small home repair businesses doing a little of everything.
For handymen and small home repair businesses doing a little of everything.
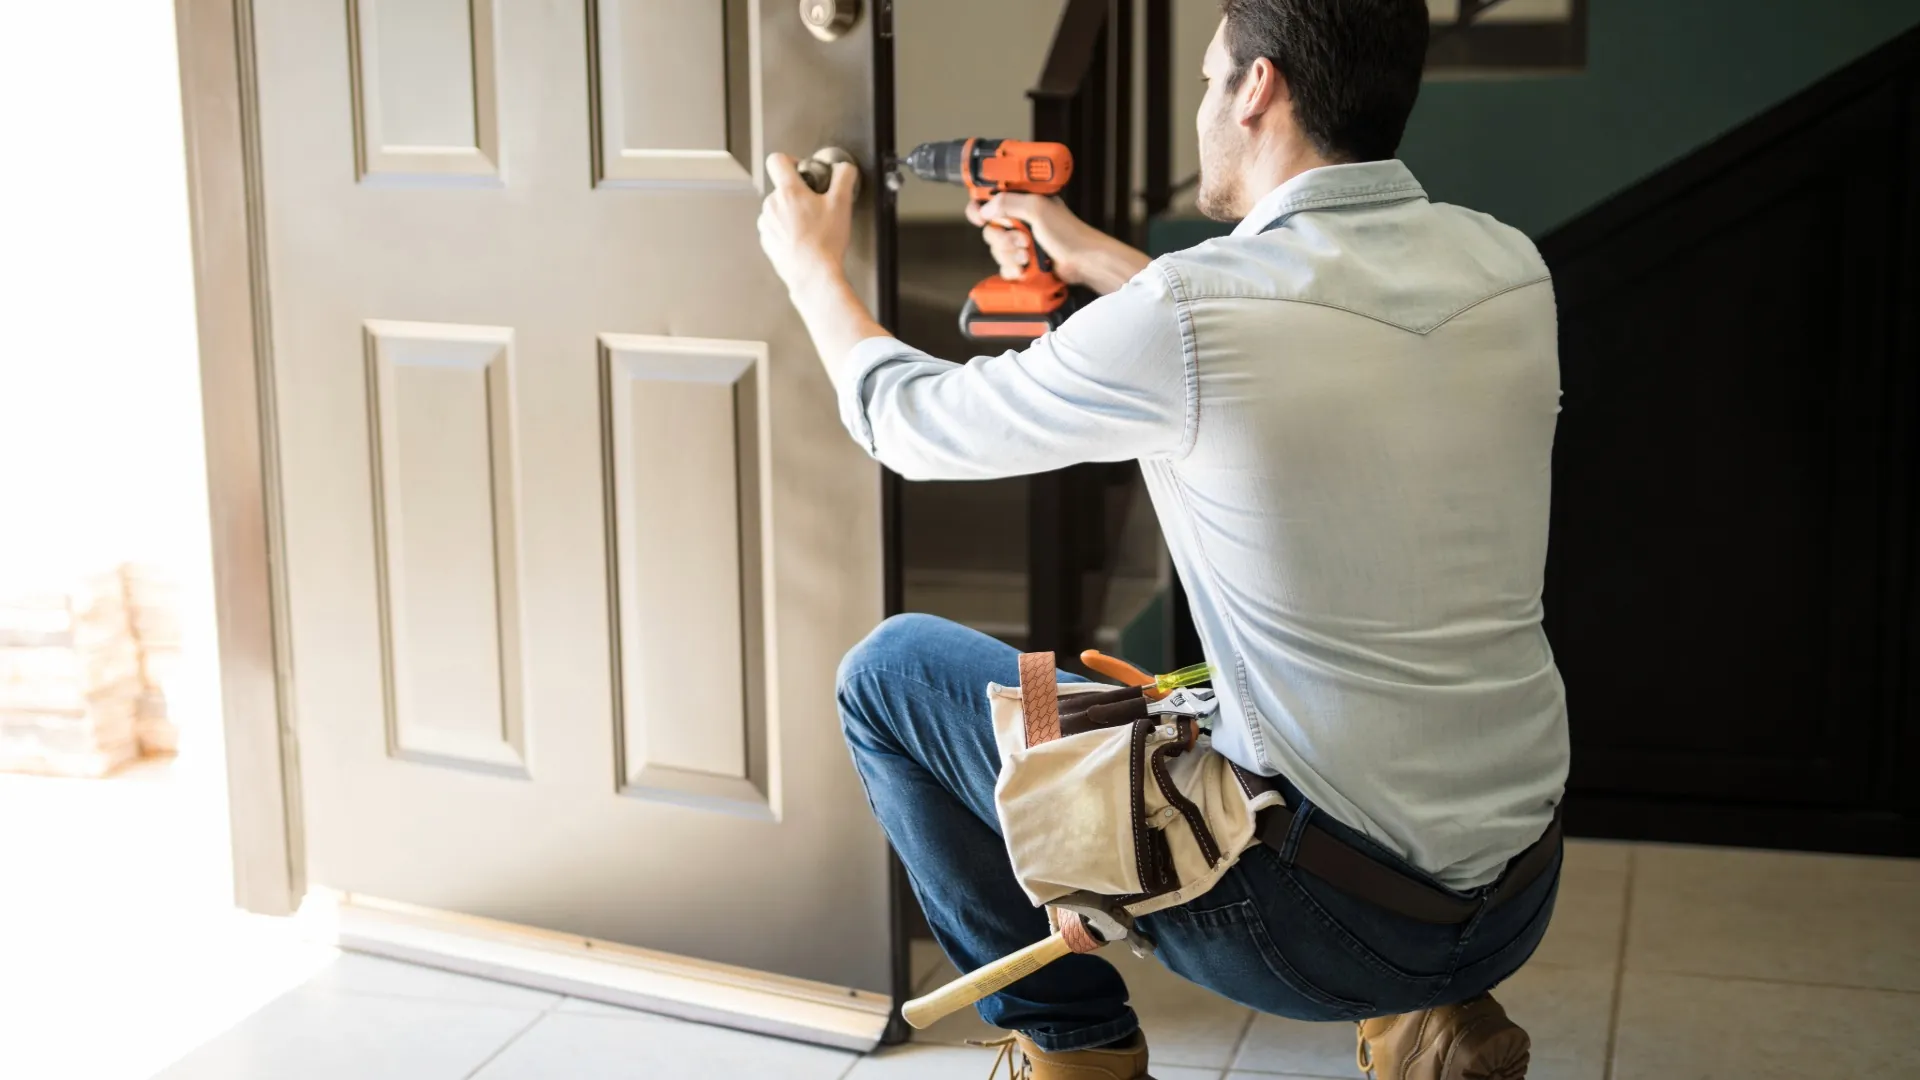
A handyman's insurance problem is variety. You hang a door on Monday, fix a deck on Tuesday and patch drywall on Wednesday, and the insurance company priced you for the jobs you listed on the application.
North Carolina has no handyman license. The limits come from other licenses: a general contractor license at $40,000 per project, and plumbing, electrical and HVAC licenses at any price. Doing licensed work without the license can also leave a claim uncovered.
General liability. Covers damage to customers' homes and injuries you cause, including completed work. Make sure every type of job you do is listed on the policy.
Inland marine (tools). Covers tools and equipment in your truck or at a job, which general liability does not.
Commercial auto. Covers the truck or van you use for work. A personal auto policy may not cover a vehicle used mainly for business.
Workers compensation. Required at three or more employees. Regular helpers can count, even if you pay them by the day.
Umbrella. Adds limits if a property manager or larger customer requires them.
Forms, endorsements and availability vary by insurance company. Your own policy governs.
No state handyman license. A general contractor license is required when the cost of the project is $40,000 or more (G.S. 87-1, NCLBGC). Below that, no state license is required for general repair work.
Trade work needs trade licenses at any price. Plumbing, heating and electrical work requires the matching state license regardless of the job's value, apart from narrow exceptions like minor plumbing part replacement and replacing lamps and fuses (G.S. 87-21, G.S. 87-43.1).
Workers comp. Employers with three or more employees regularly employed must carry workers comp (G.S. 97-2). Sole proprietors, partners and LLC members are not counted automatically but can elect to cover themselves by notifying the insurance company (NC Industrial Commission).
Vehicles. Business vehicles need at least North Carolina's 50/100/50 liability minimums on policies issued or renewed on or after July 1, 2025 (NCDOI).
The main factors insurance companies weigh:
We do not publish average prices. A licensed advisor quotes your actual operation across more than 100 insurance companies.
No state handyman license exists. A general contractor license is required for projects of $40,000 or more, and plumbing, electrical and HVAC work needs those licenses at any price.
General repair work under $40,000 per project, as long as it does not include licensed plumbing, electrical or HVAC work.
The state requires workers comp at three or more employees and auto insurance on vehicles. Liability insurance is not required by law, but most customers and property managers expect it.
General liability, tools coverage and commercial auto, with workers comp once you have helpers.
Possibly not. Claims on work you did not disclose can be denied, so list everything you do.
It depends on the services you offer, revenue, helpers and claims history. We compare many insurance companies to match your mix of jobs.
Forms, endorsements, and availability vary by insurance company. Your own policy governs.
Sizemore Insurance is an independent insurance company founded in North Carolina in 1977. Tell us what your business does and what you need to protect, and a licensed advisor will compare more than 100 insurance companies to find the coverage that fits. Insurance made just for you.
Sources: G.S. 87-1, who is a general contractor ($40,000 threshold); NC Licensing Board for General Contractors; G.S. 87-21, plumbing, heating and fire sprinkler contractor licenses; G.S. 87-43.1, electrical licensing exceptions; G.S. 97-2, workers compensation definitions (3 or more employees); NC Industrial Commission, employer insurance requirement; NC Department of Insurance, auto changes effective July 1, 2025.
Forms, exclusions, endorsements, and availability vary by carrier. This page is general information, not a policy or legal advice. Review your own policy or talk to your advisor.