Insurance in Wilmington, NC
Home, auto, flood and business insurance for Wilmington, from three local offices and a team that compares more than 100 insurance companies.
Home, auto, flood and business insurance for Wilmington, from three local offices and a team that compares more than 100 insurance companies.
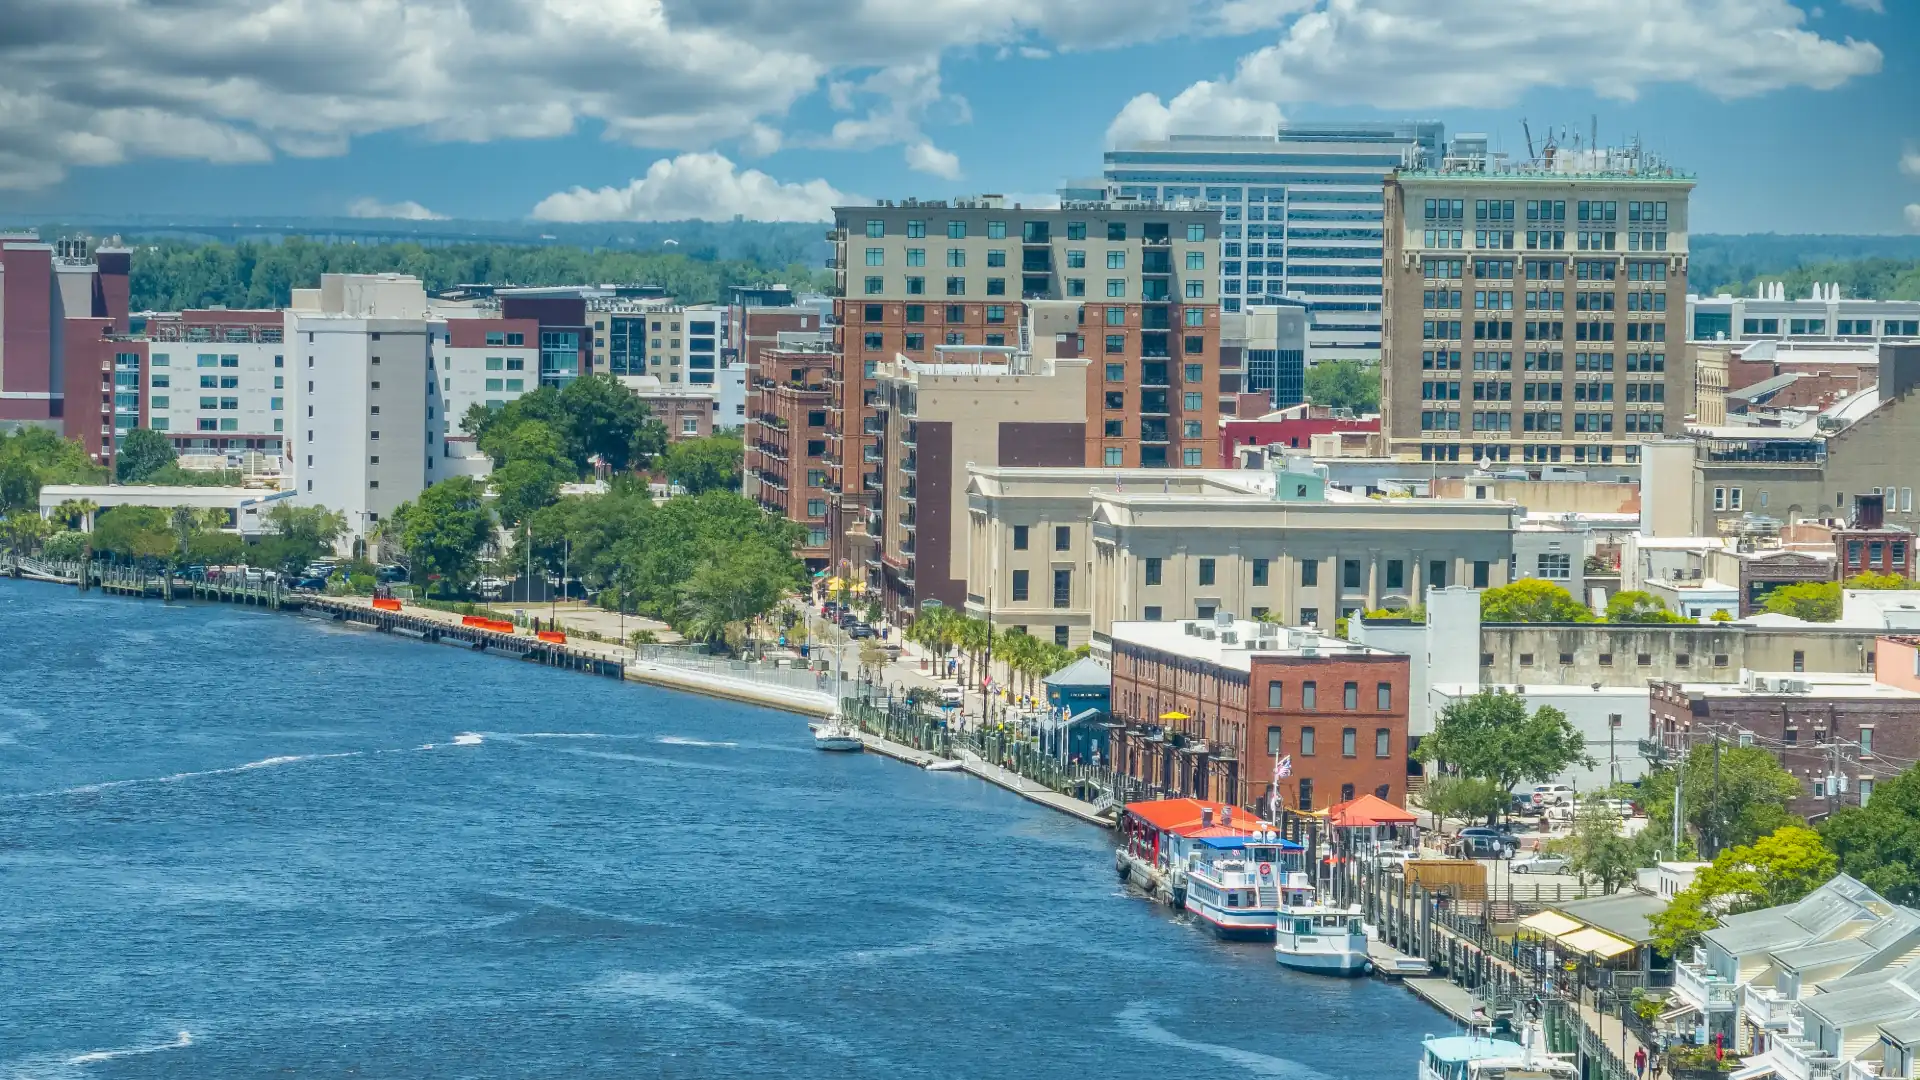
Wilmington sits on the east bank of the Cape Fear River, with the Port of Wilmington 26 miles upriver from the open sea (NC Ports). It is the county seat of New Hanover County (NCpedia), and the Census Bureau estimates 126,809 people lived here on July 1, 2025 (US Census Bureau).
That river and ocean setting is the reason insurance here works differently than it does inland. Wind, storm surge and heavy rain all show up in the claims history, and the way your home is rated depends on where it sits relative to the water.
Typical yearly cost with us: $3,832 for a home insured for $250,000 to $400,000, from our own Wilmington homeowner clients' in-force policies. See every town.
Most Wilmington homes pay for two things the inland part of the state rarely thinks about: wind and water. Many homes carry a separate wind and hail policy with its own deductible, and named storm deductibles are written as a percentage of your dwelling limit (NCDOI). Mitigation credits for qualifying roofs and construction can lower the wind part of the bill (NCDOI).
We always include wind and hail
Every home policy we place includes wind and hail. When the insurance company excludes wind, we write the wind coverage separately through the Beach Plan or another company, so you're never left without it.
The typical yearly premium our own Wilmington clients pay for rental and dwelling fire policies. See every town.
Distance to the water| Dwelling coverage | Typical yearly premium |
|---|
Compare your premium
Enter your premium to see how it compares.
Beachfront: within a quarter mile of the ocean. Near the water: within a mile of the ocean, a sound or the Intracoastal Waterway. Inland: more than a mile from the ocean and the sounds. Typical means the median: half of policyholders pay less, half pay more. Includes any separate Beach Plan wind policy. Source: Sizemore Insurance clients' in-force rental dwelling policies as of October 10, 2026, not a survey or national average (how we got these numbers). Not a quote.
Typical yearly cost with us: $1,243 for one vehicle with comprehensive and collision coverage, from our own Wilmington drivers' in-force policies. Liability only costs less. See every town.
Bridges and a few main corridors carry most Wilmington traffic, and the busiest, the Cape Fear Memorial Bridge, carries about 70,000 vehicles a day (City of Wilmington). In North Carolina your driving record moves your price under the Safe Driver Incentive Plan: a single one-point ticket raises the rate 40% (NCDOI). The state minimum is now 50/100/50 for policies written or renewed on or after July 1, 2025 (NCDOI).
Our Wilmington homeowner clients who carry flood with us pay a typical $853 a year for it.
Your homeowners policy does not cover flood (NCDOI). The City of Wilmington is not on FEMA's current Community Rating System list, so city flood policies do not carry a community discount, while unincorporated New Hanover County holds Class 7 for 15% (FEMA).
Life insurance replaces your income, pays off a mortgage or covers final expenses for the people who count on you. We write term, whole and other fixed life insurance for families and business owners, and a licensed advisor compares insurance companies for you.
Wilmington's economy runs on the port, the university, healthcare, tourism and the trades. The Port of Wilmington has nine berths and a 42 foot channel (NC Ports), and UNC Wilmington reported a record 19,895 students in fall 2025 (UNC Wilmington). Restaurants, contractors, landlords, HOAs and trucking companies here all carry coastal property exposure, so we look at wind, flood and business interruption together.
Business owners policies (BOP) and general liability
Customer injuries and property damage claims. A BOP packages liability with property for eligible small businesses.
Get Quote NowCommercial property
Your building, equipment and inventory, including wind, named storm and ordinance or law coverage.
Get Quote NowWorkers' compensation
Coverage for employees hurt on the job, plus help with certificates and the year-end audit.
Get Quote NowEmployer's liability
Lawsuits over employee injuries that fall outside workers' compensation. It is usually part of the workers' compensation policy.
Get Quote NowProfessional liability (E&O)
Claims of errors or negligence in the advice or work you provide.
Get Quote NowProfessional offices
Dentists, lawyers, accountants and medical offices: office property, general liability, professional liability and workers' compensation together.
Get Quote NowShopping centers and strip malls
Retail buildings with several tenants: the buildings, parking lot liability, lost rent, wind and flood.
Get Quote NowLessor's risk only (LRO)
For owners who lease their building to a tenant: the building, lost rent and the owner's liability.
Get Quote NowTrucking
Owner-operators and fleets: commercial auto, cargo, physical damage and federal filings.
Get Quote NowContractors
General contractors and trades: general liability, workers' compensation, tools and equipment, and builders risk.
Get Quote NowRestaurants and bars
General liability, liquor liability, property, equipment and workers' compensation.
Get Quote NowHOAs and condo associations
Master policies, common areas, wind, flood and directors and officers liability.
Get Quote NowWilmington Oleander Office
4815 Oleander Dr, Ste 101, Wilmington, NC 28403
Phone: (910) 791-1011
Hours: Monday to Friday, 8:00 AM to 5:00 PM
Get directions
Midtown Wilmington Office
2508 Independence Blvd, Suite 200, Wilmington, NC 28412
Phone: (910) 791-5447
Hours: Monday to Friday, 9:00 AM to 5:00 PM
Team: Will Parham (Insurance Advisor)
Get directions
Porters Neck Office
8024 Market Street #4, Wilmington, NC 28411
Phone: (910) 686-2138
Hours: Monday to Friday, 8:00 AM to 5:00 PM
Team: James Riley (Insurance Advisor), Earl Oxendine (Insurance Advisor)
Get directions
Our own Wilmington homeowner clients pay a typical $3,832 a year for a home insured for $250,000 to $400,000. That figure includes a separate Beach Plan wind policy for the homes that have one. Your price depends on your home, its distance to the water and the coverage you choose.
Our Wilmington drivers pay a typical $1,243 a year for one vehicle with comprehensive and collision coverage. Liability only costs less. Your drivers, vehicles and driving record set your actual price.
New Hanover County is one of the 18 coastal counties the Coastal Property Insurance Pool serves. Homes south and east of the inland waterway are in the beach area and the rest of the county is the coastal area. We check the regular market first and use the pool when it is the better or only option.
A lender requires it for homes in high-risk flood zones with a federally backed mortgage, but flooding in Wilmington is not limited to mapped zones. Florence closed every road into the city in 2018. We quote NFIP and private flood side by side.
We have three: Oleander Drive near the center of town, Independence Boulevard in Midtown, and Market Street in Porters Neck. Any of them can help with home, auto, flood and business insurance.
Sizemore Insurance is an independent insurance company founded in North Carolina in 1977, with eight offices from Charlotte to the coast. Tell us about your home, your cars and your business, and a licensed advisor will compare more than 100 insurance companies to find the coverage that fits. Insurance made just for you.
Sources: NC Ports, Port of Wilmington; NCpedia, Wilmington; US Census Bureau, city and town population estimates, Vintage 2025; NC Insurance Underwriting Association, coastal county notice; NOAA National Weather Service Wilmington, Hurricane Florence; City of Wilmington, 2021 watersheds report; City of Wilmington, Cape Fear Memorial Bridge grant; NC Department of Insurance, Windstorm and Hail; NC Department of Insurance, Fortified Homes and Mitigation Credits; NC Department of Insurance, Safe Driver Incentive Plan; NC Department of Insurance, auto rating changes effective July 1, 2025; NC Department of Insurance, Flood Insurance; FEMA, CRS eligible communities, effective October 1, 2026; UNC Wilmington, fall 2025 enrollment. Typical (median) premiums: Sizemore Insurance clients' in-force policies as of October 2026, not a survey or a quote.
Forms, exclusions, endorsements, and availability vary by insurance company. This page is general information, not a policy or legal advice. Review your own policy or talk to your advisor.