Reviewed for insurance accuracy by Brad Sizemore, Owner and CEO, NPN 6595451 · November 16, 2026
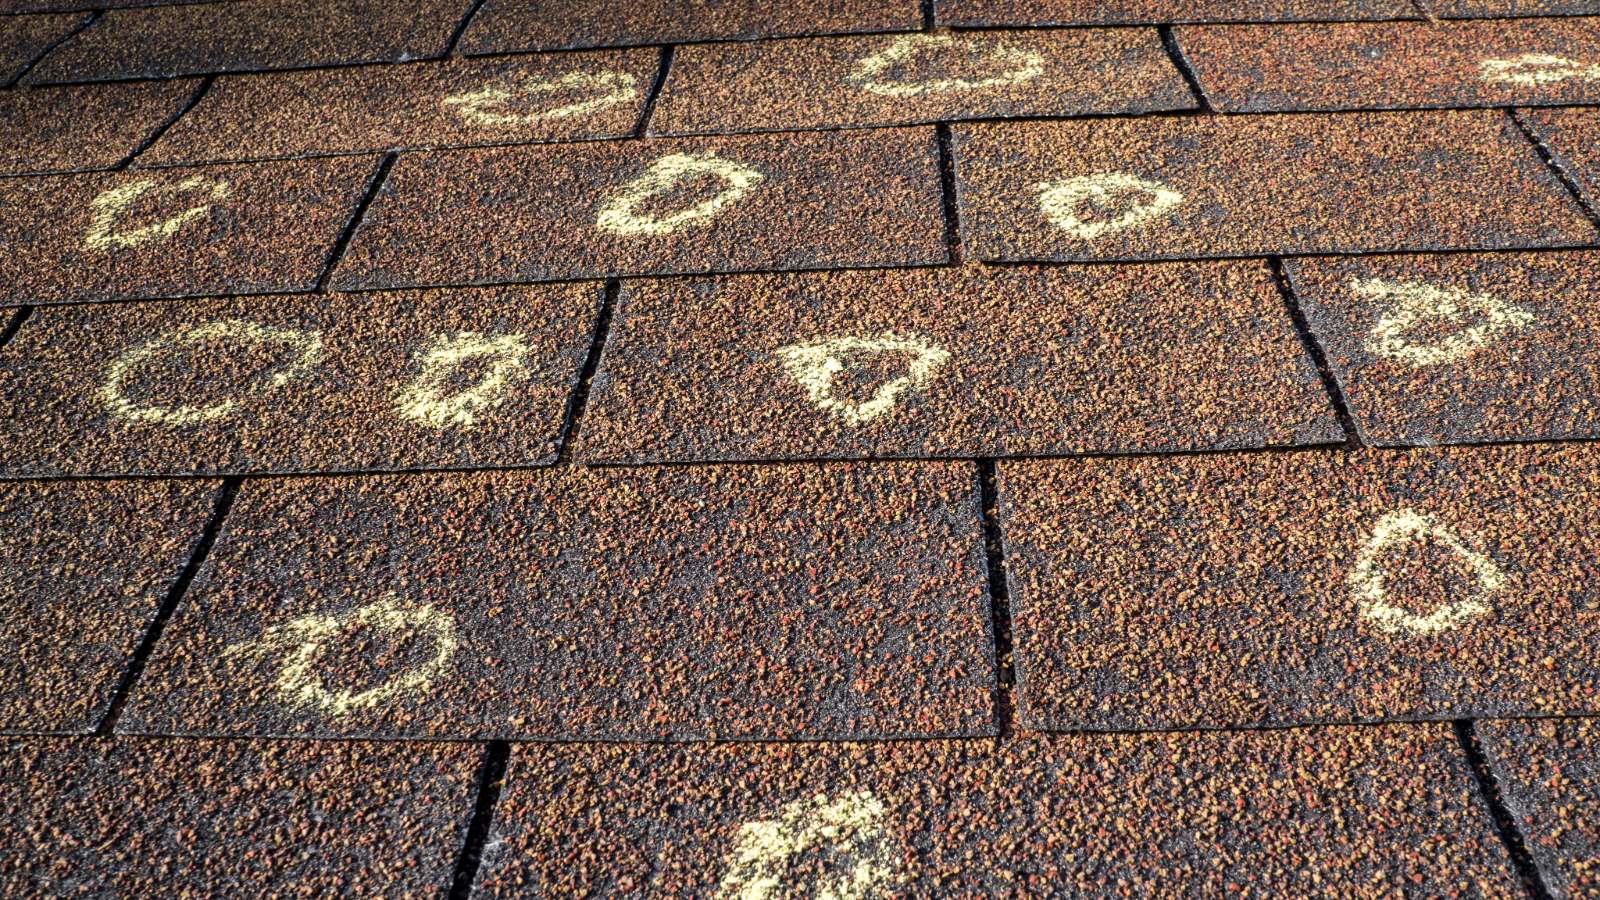
View reviewer profileA hailstorm goes through a neighborhood and within a week there are trucks on every street offering free inspections. Hail is a covered peril, and what a claim pays is decided by your deductible, your roof's age, and the endorsements on your policy.
Some of those contractors are good. What none of them know is what your policy says, and on a hail claim that is the whole question. Two houses with identical damage and identical deductibles can collect very different amounts because of two endorsements sitting in the back of their policies.
A roof payment schedule pays roof damage on an actual cash value basis according to the roof's age, inside a policy that otherwise settles at replacement cost. The older the roof, the smaller the percentage paid.
A cosmetic damage exclusion removes damage that affects appearance but not function. On metal roofing, siding, and gutters, hail dents that do not compromise performance are excluded outright.
Neither appears on the declarations page summary. Both live in the endorsement list, and both attach at renewal without a conversation.
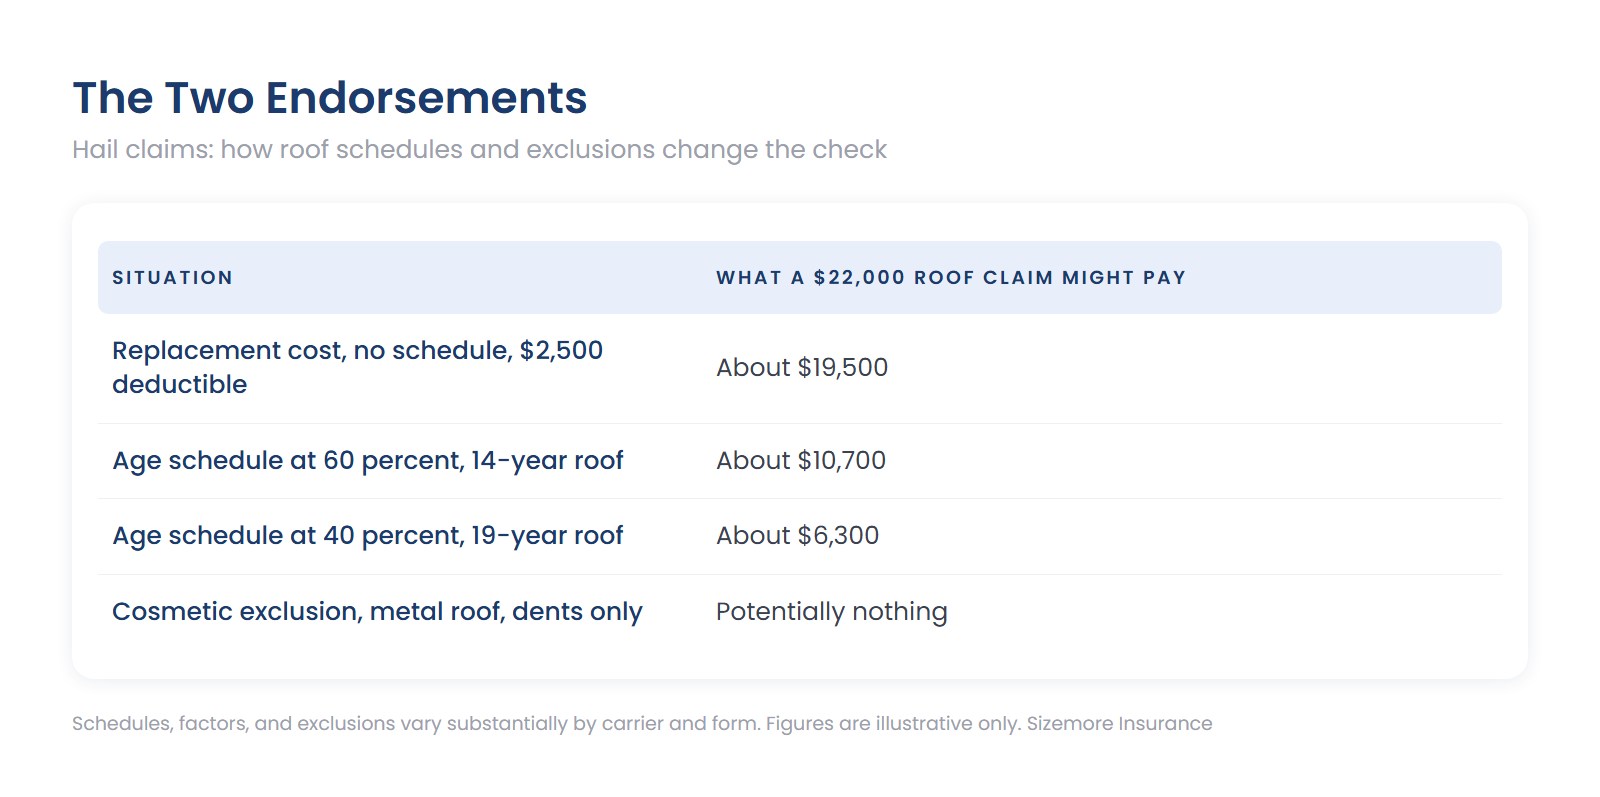
The takeaway: your roof's age and your endorsement list decide a hail claim more than the damage does.
Schedules, factors, and exclusions vary substantially by carrier and form. Figures are illustrative only.
Do not sign anything at the door. Not an inspection agreement, not a contingency contract, not an assignment of benefits. Read whatever you are handed and take your time.
Get an independent assessment. A reputable local roofer with no stake in the claim outcome, or your own inspection with photographs.
Photograph the damage yourself, including the gutters and downspout screens, which frequently show hail impact clearly, and any dented soft metal like vents and flashing.
Check your policy before you file. Roof age, whether a schedule is attached, whether a cosmetic exclusion applies, and what your deductible is, including any separate wind and hail deductible.
Then decide. If the likely recovery after the schedule and the deductible is small, filing may cost more in frequency than it returns.
Call us before you file, not after. That conversation takes ten minutes and it is the most valuable ten minutes in this process.
Cosmetic and functional damage is genuinely contested. Denting that compromises a coating, opens a path for corrosion, or affects a fastener seal is an argument for functional damage. That argument is won with a qualified inspection and documentation, not a phone call.
Matching is not guaranteed. If part of a roof slope or one elevation of siding is damaged and the material is discontinued, most policies owe the damaged portion rather than a full replacement for uniformity.
Frequency is what drives non-renewal. In the current market, two or three claims in a short window matters more than one large one. A marginal hail claim can cost you the carrier.
An assignment of benefits transfers your claim rights. Some contractors present one alongside a work authorization. Understand what you are signing and involve your advisor first.
A new roof changes your position going forward. It improves eligibility, may remove a schedule, and resets the age clock. If you were near a replacement anyway, a hail event can be the right moment.
Correct a wrong roof date now. Under an age schedule, a carrier record showing the original roof instead of your 2019 replacement is worth thousands. Send the invoice and permit.
Does homeowners insurance cover hail damage?
Hail is a covered peril. What it pays depends on your deductible, any roof payment schedule, and any cosmetic damage exclusion.
What is a cosmetic damage exclusion?
An endorsement excluding damage that affects appearance without impairing function, most often hail dents on metal.
How do I know if my roof is on a schedule?
Read the endorsement list, not the declarations summary. Look for anything referencing roof surfacing, roof settlement, or windstorm and hail loss settlement.
Should I let a door-knocking roofer file for me?
Get an independent assessment and read anything before signing. Do not assign your claim rights without understanding the consequence.
Will one hail claim raise my rates?
Likely, and the larger risk is frequency. Two or three claims in a short window is what leads to non-renewal.
My roof is 20 years old and undamaged. Does that matter?
Yes, for eligibility and pricing independent of condition. Age is a proxy underwriters use.
Sizemore Insurance is an independent insurance company founded in North Carolina in 1977. Send us your endorsement list and your roof age and we will tell you what a hail claim would actually pay on your house. Insurance made just for you.
Sources: North Carolina Department of Insurance, consumer guidance on homeowners claims, roofing contractors and assignment of benefits (ncdoi.gov); North Carolina Rate Bureau, homeowners policy forms and endorsements (ncrb.org).
Endorsements, schedules, factors, and exclusions vary substantially by carrier and form. Figures are illustrative only. Nothing here is a coverage determination. Review your own policy or talk to your advisor.
Coverage details: North Carolina Home Insurance