Reviewed for insurance accuracy by Brad Sizemore, Owner and CEO, NPN 6595451 · November 16, 2026
View reviewer profileA covered slip with a lift, decking, power, and water can run well into six figures to replace. On many lake properties it is the second most valuable structure after the house. Homeowners usually covers a dock, boathouse, or lift only as an other structure under a shared or reduced limit, sometimes not at all, and ice, wave action, and wear are frequently excluded.
It is also, on a standard homeowners policy, treated as a shed with a percentage limit and in some cases not treated at all.
Three possibilities, and you need to know which one applies to you.
Covered under other structures, Coverage B. The dock competes for the same limit as the detached garage, the shed, and the fence. Usually a percentage of the dwelling limit, commonly 10 percent.
Covered with a specific sublimit for structures in or over water. Some forms cap docks and boathouses separately and at a lower figure than the general other structures limit.
Excluded. Some forms exclude structures located in or over water entirely, or exclude specified perils on them such as ice, freezing, and wave action.
That third category is the one that surprises people, and it is not rare.
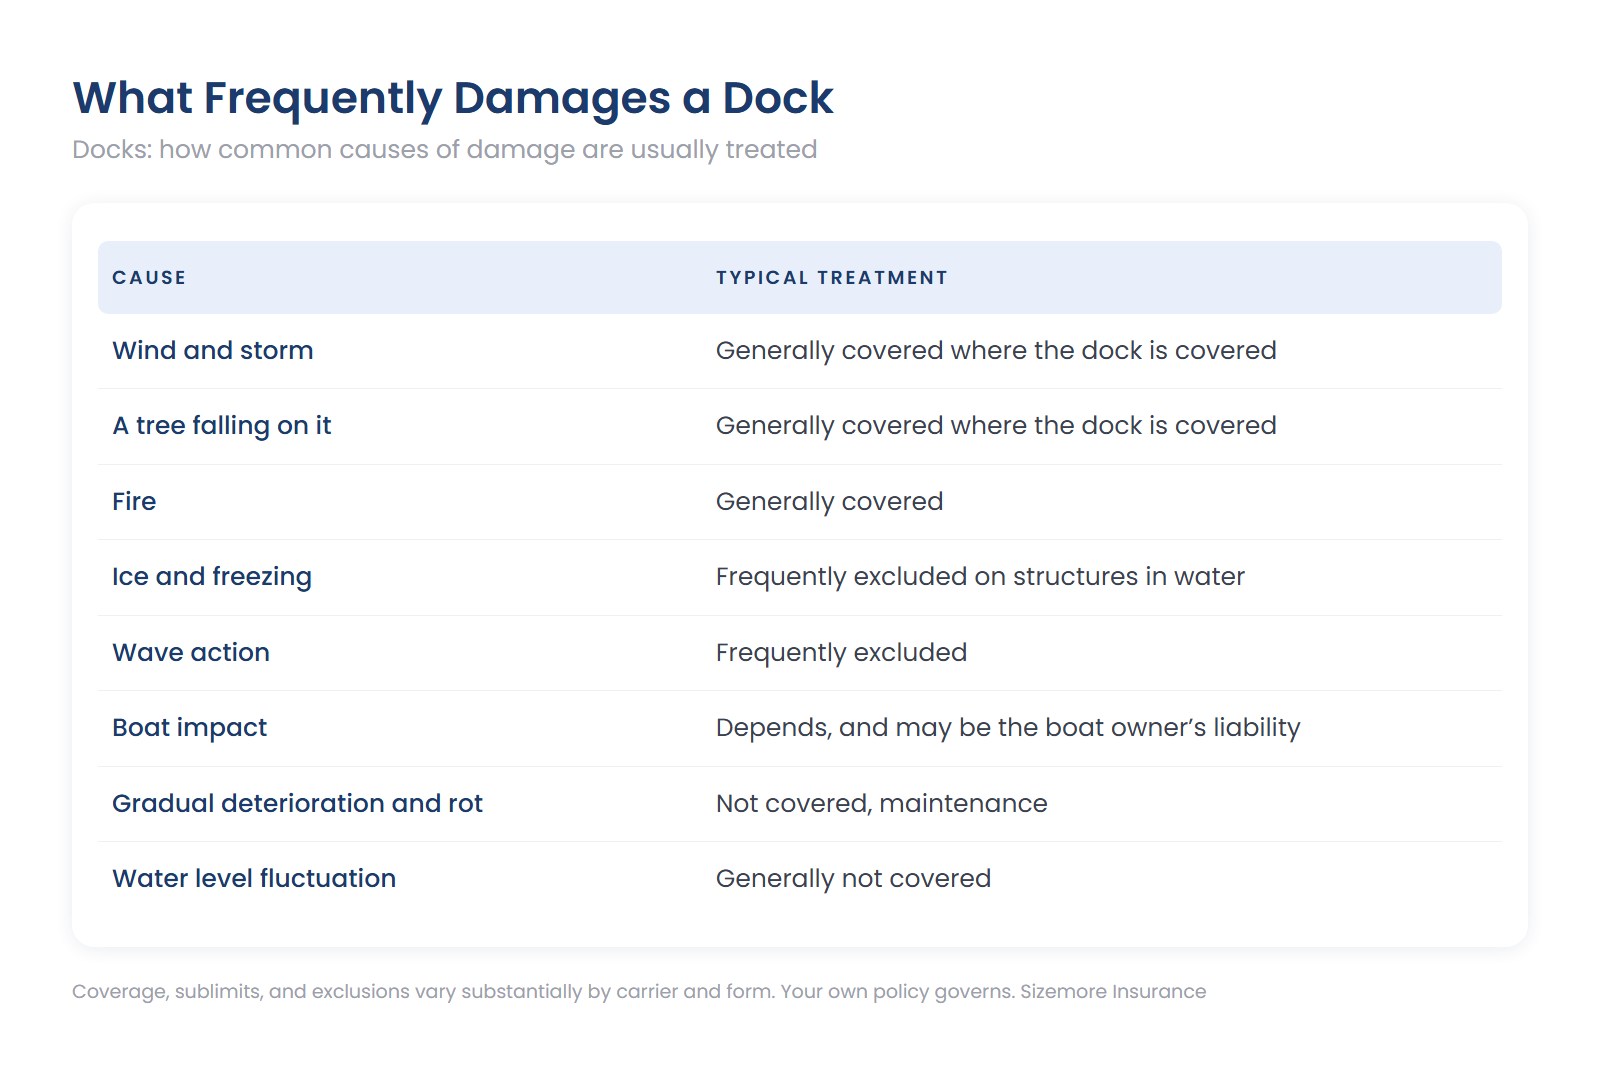
The takeaway: the perils most likely to damage a dock are the ones most likely to be excluded on it. Ice, wave action, and deterioration account for a great deal of dock damage.
Coverage, sublimits, and exclusions vary substantially by carrier and form. Your own policy governs.
Find out which of the three categories applies to you. It is in the endorsement list and in the other structures section, not on the declarations summary.
Get a replacement cost figure for the dock. Ask a builder what the structure would cost to rebuild today, including the lift, the roof, the decking, the electrical, and the water. Most owners have never asked and most numbers are higher than expected.
Add up all your other structures and compare the total to your Coverage B limit. Dock, boathouse, lift, seawall, detached garage, shed, fence, pump house.
Ask about scheduling the dock specifically rather than relying on the shared percentage. Some carriers will list it separately with its own limit.
If the standard market will not cover it adequately, ask about a specialty market. Docks and boathouses can be written separately.
Photograph it annually, from several angles, including the lift and the underside of the decking. This is what establishes pre-loss condition, and deterioration arguments are the most common dispute on dock claims.
Permits matter. On several Carolina lakes the shoreline and lake bed are managed by a utility, and dock construction, modification, and repair require permits. A nonpermitted structure is a problem for coverage and for the rebuild after a loss.
Rebuilding requires a permit too. After a loss, replacing the dock is a permitted activity, and current standards may differ from what was there. That is an ordinance and law question in substance even where the policy language does not use the phrase.
Liability at the dock is significant. Diving, swimming, ladders, and electricity near water. Electric shock drowning is a real hazard around boat lifts and dock wiring, and ground fault protection on dock circuits is worth confirming.
A boat lift is machinery. Motor and mechanism failure is not a property peril. Equipment breakdown coverage on a homeowners policy may reach some of it, and it is worth asking.
Boats stored on the lift are not covered by the homeowners policy in any meaningful way. That is the boat policy.
Deterioration is the most common denial. A dock is a wooden structure in water and it ages. Photographs and maintenance records are what separate storm damage from wear.
Does homeowners insurance cover a dock?
Sometimes, under other structures, sometimes at a lower sublimit, and sometimes not at all. Read your form.
Is ice damage to my dock covered?
Frequently not. Ice and freezing are commonly excluded on structures in or over water.
How much is my dock worth?
Ask a builder for a current replacement figure. Owners routinely underestimate it by half.
Can I schedule the dock separately?
Some carriers will. It is worth asking, especially where the shared other structures limit is inadequate.
Do I need a permit to rebuild after a storm?
On most managed Carolina lakes, yes. Confirm with the lake manager before work begins.
Is my boat covered while on the lift?
Not meaningfully by the homeowners policy. That is what a boat policy is for.
Sizemore Insurance is an independent insurance company founded in North Carolina in 1977. Tell us what is on your shoreline and we will tell you whether it is actually insured. Insurance made just for you.
Sources: North Carolina Rate Bureau, North Carolina homeowners policy forms, including other structures coverage and the exclusions for structures in or over water (ncrb.org); North Carolina Department of Insurance, consumer guidance on homeowners coverage (ncdoi.gov).
Coverage, sublimits, exclusions, and availability vary substantially by carrier and form. Shoreline permitting requirements vary by lake and utility. Review your own policy or talk to your advisor.
Coverage details: North Carolina Home Insurance