

There is a middle ground on this coast that gets overlooked in the conversation about beach houses.
A home in Leland, or Hampstead, or Newport, is not an oceanfront property and it is not an inland property either. It sits in a territory where wind matters, where flood risk is real and frequently unmapped, and where the standard market is available but selective.
Owners in that middle ground often carry policies built as though the house were inland, because that is how they were quoted. Here is what actually changes.
Wind is usually included, and not always. Unlike the barrier islands, most coastal mainland homes can get windstorm coverage inside the homeowners policy. Closer to the water, or on an older home, it may still be excluded and written separately. Check the policy rather than assuming.
The deductible structure is where the surprise is. Even where wind is included, many of these policies carry a separate wind and hail or named storm deductible expressed as a percentage of the dwelling limit. Two percent of a $450,000 home is $9,000, and the homeowner is usually thinking about the $1,000 on the front page.
Flood risk extends well past the mapped zones. Sound-side, creek, and stormwater flooding reach homes that are nowhere near the ocean and outside any high-risk zone. Florence made that point across all three counties.
Roof age drives eligibility. More so here than inland. Carriers apply age thresholds, and past one the options narrow to a roof payment schedule, a higher rate, or a decline.
Trees are a real exposure. Large pines and oaks close to structures are a wind hazard underwriters look at, and they are behind a great many of the claims we actually see in these counties.
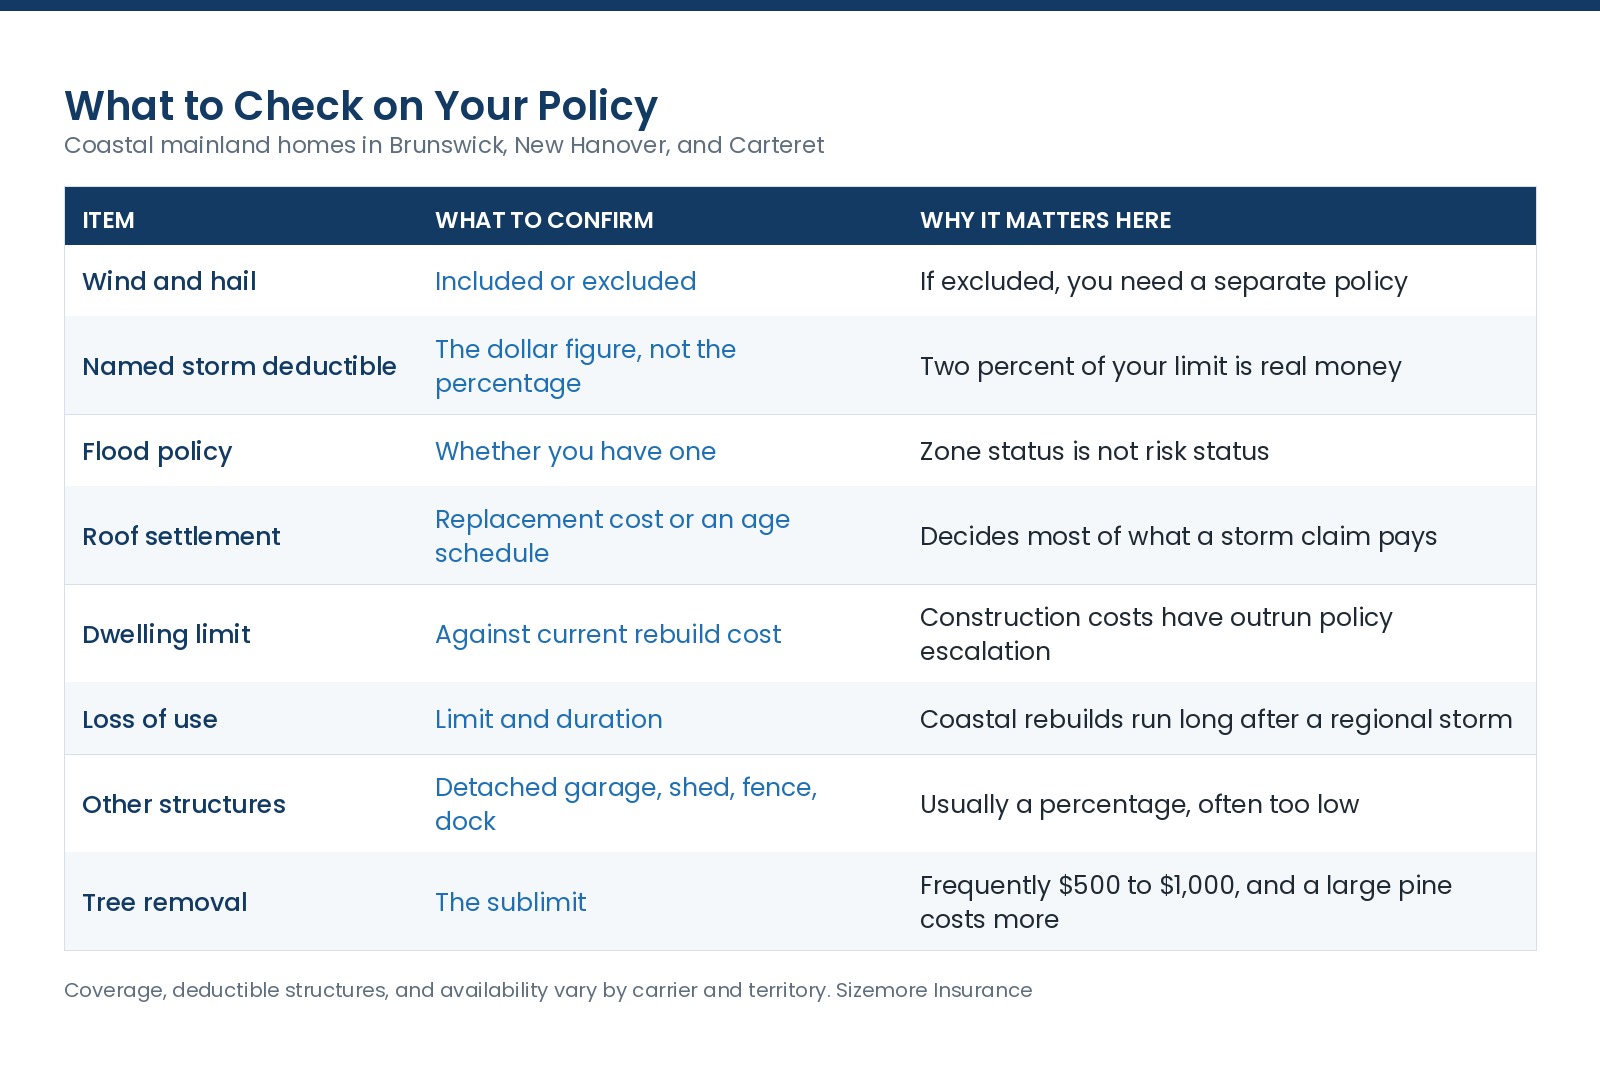
The takeaway: the two items that surprise homeowners here are the percentage storm deductible and the absence of a flood policy. Both are fixable in a phone call and neither can be fixed after a storm.
Coverage, deductible structures, and availability vary by carrier and territory. Review your own declarations page.
I want to spend a paragraph here because this is the gap I see most in these three counties.
Flooding regularly reaches homes outside mapped high-risk zones, as Florence demonstrated across all three counties. Stormwater that has nowhere to go, creeks out of their banks, and sound-side rise all reach houses that are nowhere near the ocean. A flood zone map describes what a lender requires. It does not describe what water does.
Coverage outside a high-risk zone is generally inexpensive. On a mainland coastal home it is frequently one of the least expensive line items in the entire household insurance program, and it is protecting against the loss that produces total interior destruction.
The 30-day waiting period means it cannot be bought once a storm has a name. If you have been meaning to look at it, the right month is any month that is not hurricane season.
Coastal is not one territory. Within Brunswick County alone, a home in Calabash, a home in Leland, and a home on Oak Island are three different rating situations. A quote for one tells you nothing about another.
Second homes are rated differently. A house you do not occupy full time is a different underwriting question, and if it is rented at all it may need a different form entirely.
Older homes narrow the market. Electrical panel type, plumbing material, and roof age all determine which carriers will write the house. A 1978 home with a fuse panel and original plumbing is a harder placement than its condition suggests.
Enhanced roof construction now earns credits. The dwelling rate settlement announced in April 2026 built in mitigation credits for fortified homes and roofs in many eastern North Carolina territories. If a re-roof is on your horizon, specifying it to those standards is worth pricing.
Detached structures are underinsured constantly. Other structures coverage is usually a percentage of the dwelling limit and it has to cover the detached garage, the shed, the fence, and in some cases a dock. Add them up before assuming the percentage is enough.
Wind-driven rain is judged on evidence. Photograph your roof, flashing, and openings on a clear day. That is what separates a covered wind loss from a maintenance argument.
Is wind covered on a coastal mainland home in North Carolina?
Usually yes inside the homeowners policy, and not always. Look for a windstorm and hail exclusion on your form.
Do I need flood insurance if I am not in a flood zone?
Zone designation determines what a lender requires, not whether your house can flood. Outside a high-risk zone the coverage is typically inexpensive.
Why is my deductible a percentage?
Percentage wind and named storm deductibles are common in coastal territories. Multiply it by your dwelling limit to see the real number.
Will my premium keep going up?
North Carolina homeowners rates rose 7.5 percent on June 1, 2025 and again on June 1, 2026 under a negotiated settlement, and insurers cannot request another base rate increase before June 2027.
Does my policy cover tree removal?
Usually with a sublimit, frequently $500 to $1,000, which does not cover a large pine. Ask what yours is.
My house is 40 years old. Does that matter?
Yes, primarily through roof, electrical, and plumbing. Documented updates meaningfully widen your market.
We have been an independent insurance company in North Carolina since 1977 and we have handled a lot of storms in these three counties. Send us your declarations page and the address and we will tell you what is missing. Insurance made just for you.
Coverage, deductible structures, credits, and availability vary by carrier, territory, and property. Review your own declarations page or talk to your advisor.