Insurance in Charlotte, NC
Home, auto, flood and business insurance for Charlotte, from our uptown office on South Tryon Street.
Home, auto, flood and business insurance for Charlotte, from our uptown office on South Tryon Street.
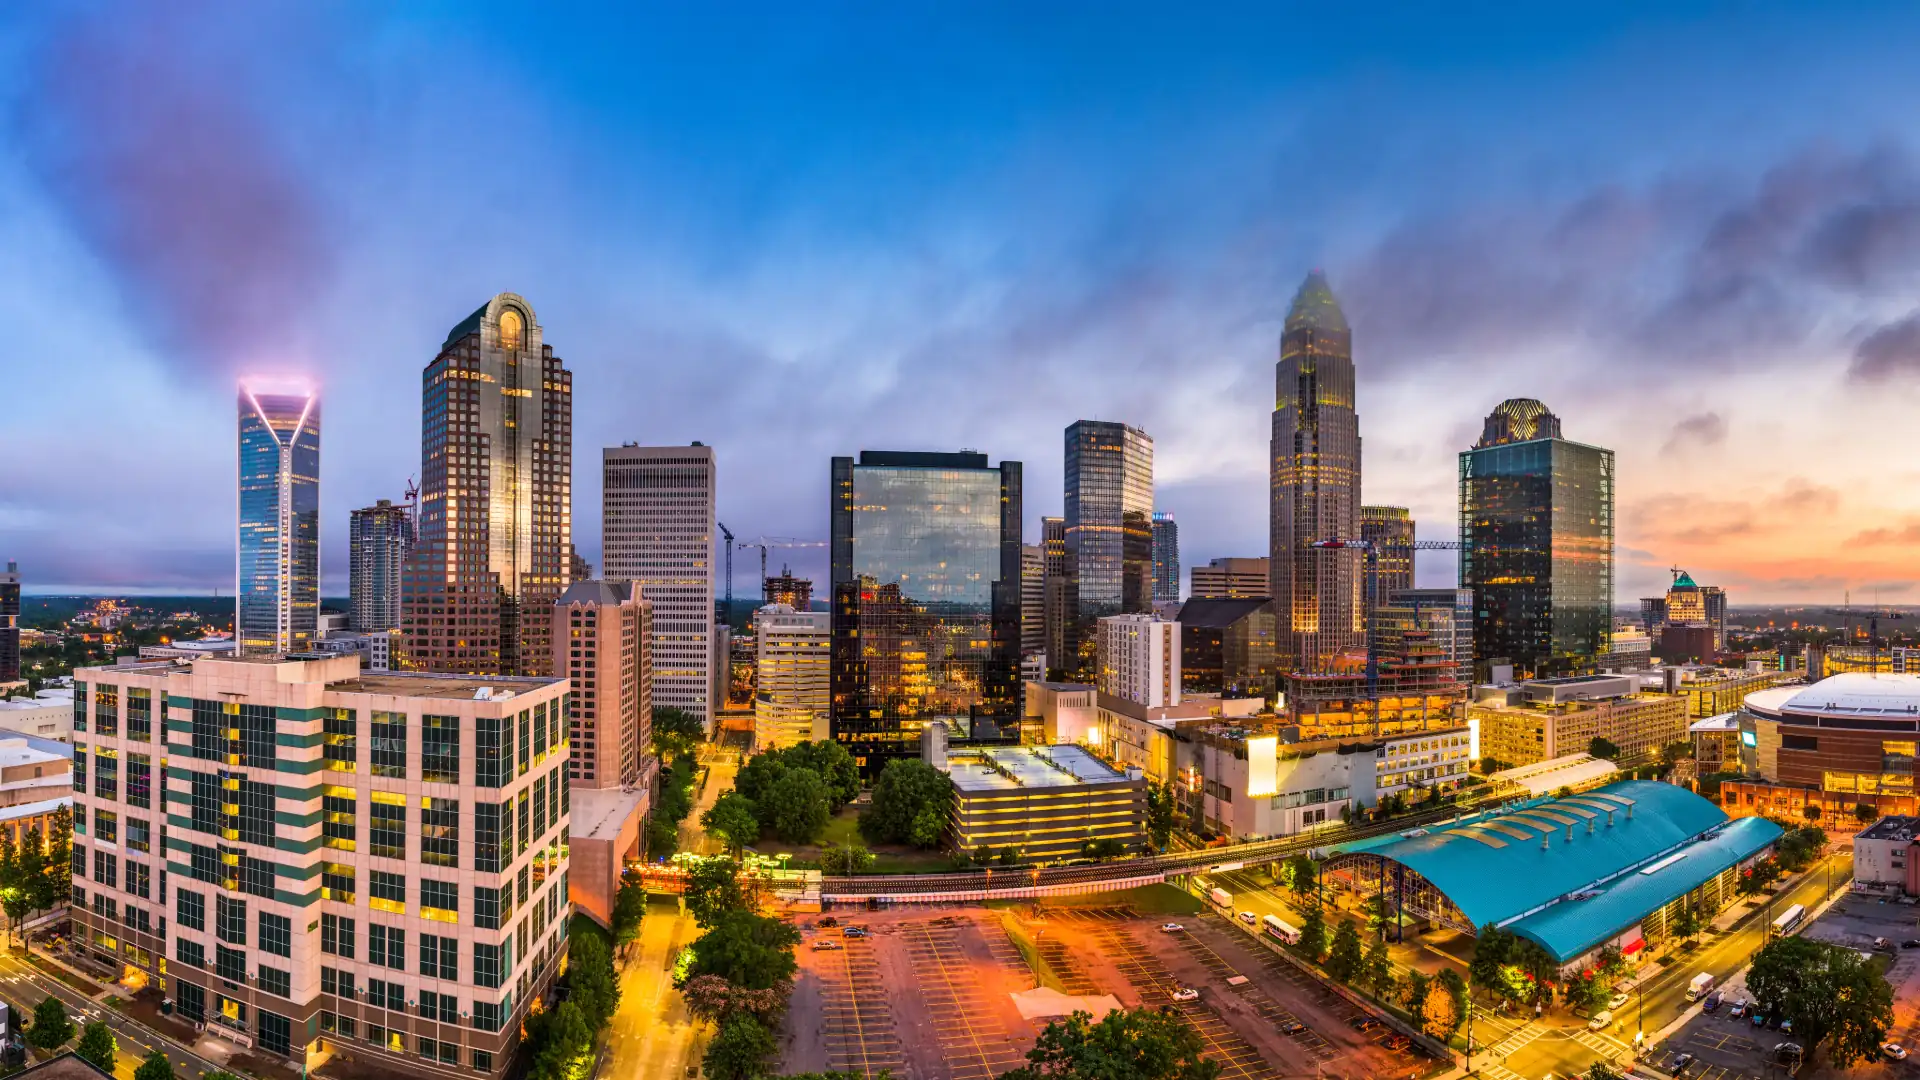
Charlotte is North Carolina's largest city and added roughly 70,000 people between April 2020 and July 2024 (NC OSBM). Our Charlotte office is uptown on South Tryon Street.
Charlotte is far from the coast, but it is not free of weather risk. Urban creeks flood fast, ice storms take down trees and power lines, and tornadoes have crossed Mecklenburg County. That is what drives insurance here.
Curious what coverage costs?
See how home and auto premiums vary by home value, coverage and location with our cost tools. For a price on your own home and cars, get a quote and an advisor will shop it for you.
Charlotte homes are not in the Beach Plan counties, so wind is usually part of the regular homeowners policy (NCIUA). What drives price here is rebuilding cost, roof age, tree exposure and the weather the Piedmont actually gets: wind, hail, ice and the occasional tornado (City of Charlotte, National Weather Service). We compare companies on coverage first, then price.
Charlotte traffic is dense, and Mecklenburg County recorded 37,228 reportable crashes in 2024 (NCDOT). Under the Safe Driver Incentive Plan, a single one-point ticket raises the rate 40% (NCDOI). The state minimum is 50/100/50 for policies written or renewed on or after July 1, 2025 (NCDOI), and higher limits are worth pricing in a city this busy.
Your homeowners policy does not cover flood (NCDOI). Charlotte's CRS Class 2 rating gives NFIP policies in the regulated floodplain up to 40% off and homes outside it 10% off (FEMA, Storm Water Services).
Life insurance replaces your income, pays off a mortgage or covers final expenses for the people who count on you. We write term, whole and other fixed life insurance for families and business owners, and a licensed advisor compares insurance companies for you.
Charlotte is a business center, and we insure the companies that keep it running: restaurants, bars, contractors, trucking firms, landlords, HOAs and condo associations. We write general liability, property, workers comp, commercial auto and umbrella coverage.
Business owners policies (BOP) and general liability
Customer injuries and property damage claims. A BOP packages liability with property for eligible small businesses.
Get Quote NowCommercial property
Your building, equipment and inventory, including wind, named storm and ordinance or law coverage.
Get Quote NowWorkers' compensation
Coverage for employees hurt on the job, plus help with certificates and the year-end audit.
Get Quote NowEmployer's liability
Lawsuits over employee injuries that fall outside workers' compensation. It is usually part of the workers' compensation policy.
Get Quote NowProfessional liability (E&O)
Claims of errors or negligence in the advice or work you provide.
Get Quote NowProfessional offices
Dentists, lawyers, accountants and medical offices: office property, general liability, professional liability and workers' compensation together.
Get Quote NowShopping centers and strip malls
Retail buildings with several tenants: the buildings, parking lot liability, lost rent, wind and flood.
Get Quote NowLessor's risk only (LRO)
For owners who lease their building to a tenant: the building, lost rent and the owner's liability.
Get Quote NowTrucking
Owner-operators and fleets: commercial auto, cargo, physical damage and federal filings.
Get Quote NowContractors
General contractors and trades: general liability, workers' compensation, tools and equipment, and builders risk.
Get Quote NowRestaurants and bars
General liability, liquor liability, property, equipment and workers' compensation.
Get Quote NowHOAs and condo associations
Master policies, common areas, wind, flood and directors and officers liability.
Get Quote NowCharlotte Office
101 S. Tryon Street, Suite 2700, Charlotte, NC 28280
Phone: (910) 791-1011 (main line)
Call our main line and we will connect you with your advisor.
Get directions
Yes. Our Charlotte office is at 101 S. Tryon Street, Suite 2700. Call our main line at (910) 791-1011 and we will connect you with your advisor.
Rebuilding cost, roof age, the home's claims history and Piedmont weather such as wind, hail, ice and falling trees. Charlotte is not in a Beach Plan county, so wind is usually part of the regular homeowners policy. We compare more than 100 insurance companies to find the right fit.
Yes. The City of Charlotte holds FEMA Community Rating System Class 2, the best in North Carolina, worth up to 40% off NFIP policies in the regulated floodplain. Buildings outside the regulated floodplain receive a 10% discount.
Charlotte's creeks can rise fast; Irwin Creek and Little Sugar Creek rose 20 feet or more in the July 1997 storm. Homeowners policies do not cover flood. We quote NFIP and private flood side by side.
For policies written or renewed on or after July 1, 2025, the minimum is $50,000 per person and $100,000 per accident for bodily injury and $50,000 for property damage. Uninsured motorist coverage is also required.
Sizemore Insurance is an independent insurance company founded in North Carolina in 1977, with eight offices from Charlotte to the coast. Tell us about your home, your cars and your business, and a licensed advisor will compare more than 100 insurance companies to find the coverage that fits. Insurance made just for you.
Sources: NC Office of State Budget and Management, "Raleigh surpassed 500,000 people in 2024"; FEMA, CRS eligible communities, effective October 1, 2026; Charlotte-Mecklenburg Storm Water Services, Community Rating System; USGS, Flooding in Charlotte (Fact Sheet 036-98); City of Charlotte, the 2002 ice storm; NOAA National Weather Service Greenville-Spartanburg, March 3, 2012 tornado; NCDOT, 2024 Mecklenburg County crash profile; NCJUA and NCIUA, coverage and eligibility; NC Department of Insurance, Safe Driver Incentive Plan; NC Department of Insurance, auto rating changes effective July 1, 2025; NC Department of Insurance, Flood Insurance.
Forms, exclusions, endorsements, and availability vary by insurance company. This page is general information, not a policy or legal advice. Review your own policy or talk to your advisor.