
Wind and hail is not a policy. It is a peril, and how it gets covered depends entirely on where the property sits.
Inland, it is one of many causes of loss inside an ordinary policy and nobody thinks about it. On the coast, it gets carved out, priced separately, and frequently written by a different company than the one covering everything else.
Understanding that structure is the first step to understanding a coastal insurance program.
Wind and hail covers damage from wind and from hail. On a building that means the roof, the siding, the windows, the openings, and whatever the wind lets in afterward. On a boat it means the vessel. On a vehicle it is comprehensive coverage and it is not separated out at all.
What it does not cover is water that rose. Storm surge, a creek out of its banks, and rising water are flood, always, and they are a separate policy.
That one distinction accounts for most of the confusion after a hurricane.
Standard carriers price risk they can spread across a large, geographically diverse book. Hurricane wind does not spread. It arrives on one coastline on one day and damages thousands of structures at once.
Where that exposure concentrates, carriers manage it by excluding the peril and letting somebody else write it. That is not a failure of the market. It is the market working the way exposure concentration forces it to.
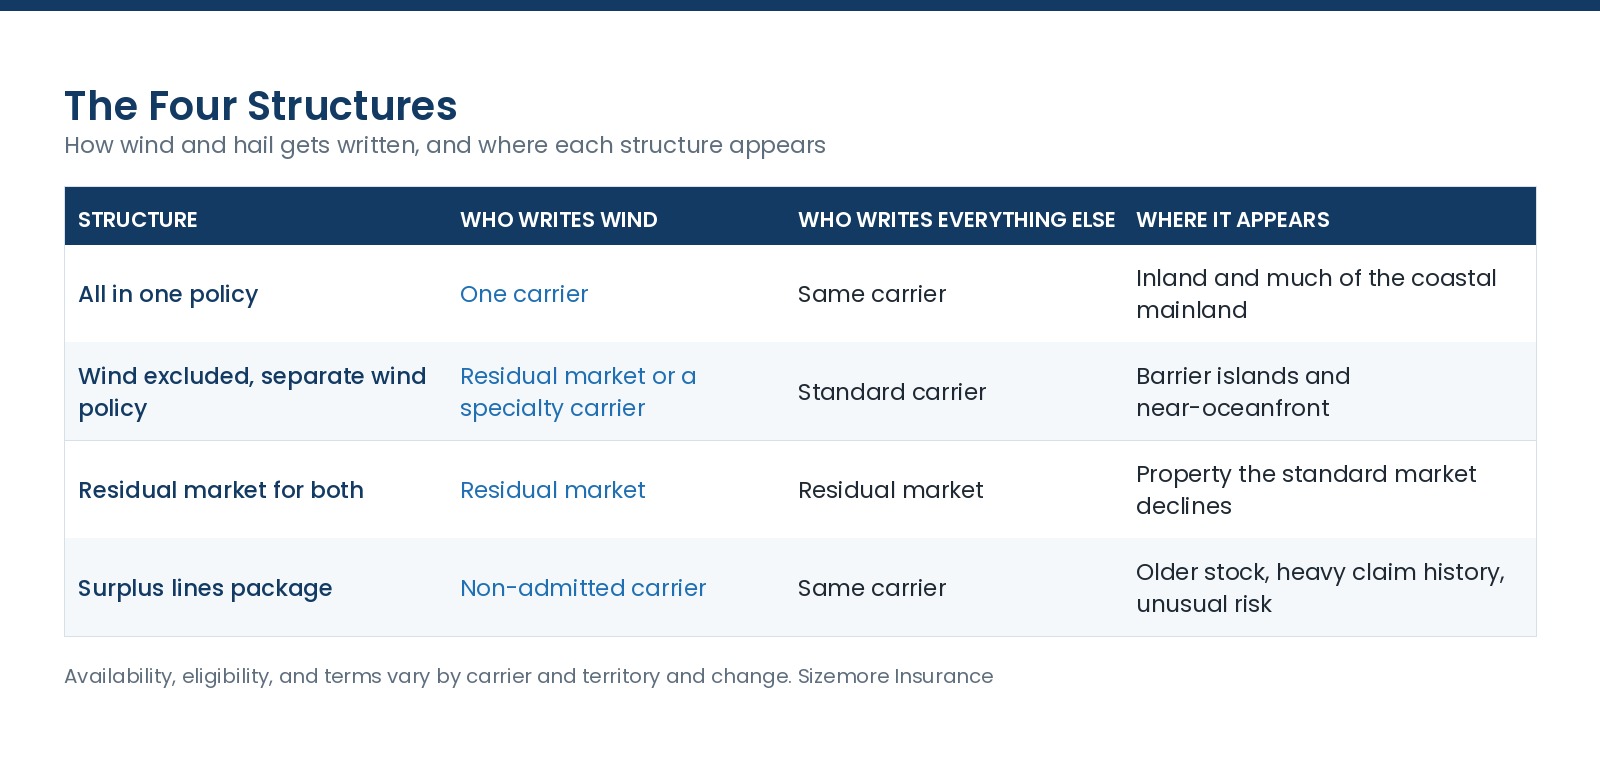
The takeaway: two coastal quotes are not comparable until you know which structure each one is. Premium alone tells you nothing.
Availability, eligibility, and terms vary by carrier and territory and change. Confirm what applies to your property.
Two policies, two deductibles. A storm producing wind damage and interior water damage can involve both, each with its own deductible.
Two adjusters, and an argument about which policy owns which damage. Documentation is what settles it.
Liability lives in the companion policy, not the wind one. A wind-only policy generally carries no liability, and confirming it exists somewhere is a step people skip.
Limits may be capped in the residual market, which on a higher-value property leaves a layer needing excess coverage above it.
Loss of use terms differ, and residual market coverage is generally narrower on that than a standard policy.
Renewal dates differ, which means two things to track rather than one.
The deductible is usually a percentage. On a coastal wind policy the deductible is frequently a percentage of the insured value rather than a flat amount, and it applies per named storm.
Triggers vary. Named storm, hurricane, and wind and hail are three different phrases with different reach, and two policies showing the same percentage can respond differently to the same weather.
Roof condition drives eligibility, not just price. Past certain thresholds the standard market declines and the residual market is what is left.
Mitigation is now recognized in rate structures in many eastern North Carolina territories, which changes the math on roof work you were going to do anyway.
This applies to commercial property too, with the same structures and the same residual mechanisms.
A boat is a fourth category with its own named storm deductible and haul-out considerations.
Is wind and hail included in my policy?
Inland, usually. In coastal territories frequently not. Check the form for a windstorm and hail exclusion.
Why would a carrier exclude wind?
Because hurricane exposure concentrates rather than spreading, which is the opposite of how insurance pricing works.
Does wind and hail cover storm surge?
No. Surge is rising water and it requires a flood policy.
If I have two policies, which one do I call?
Both, the same day, and document everything before anything is moved.
Do I still have liability if my wind policy is separate?
It comes from the companion policy, not the wind one. Confirm it is there.
Can I get wind back into one policy?
Sometimes, and roof condition is usually the lever. Ask us to re-market annually.
We have been an independent insurance company in North Carolina since 1977 and we have placed a great deal of coastal wind. Send us your declarations page and we will tell you which structure you are in and whether it is the right one. Insurance made just for you.
Coverage, availability, eligibility, and residual market terms vary and change. Review your own policy or talk to your advisor.