
This is one of the most important ten minutes a coastal property owner can spend, and it requires nothing but your policy documents.
If windstorm and hail is excluded from your policy and you do not have a separate wind policy, that is not a gap to address at renewal. It is the loss most likely to happen to you, uncovered.
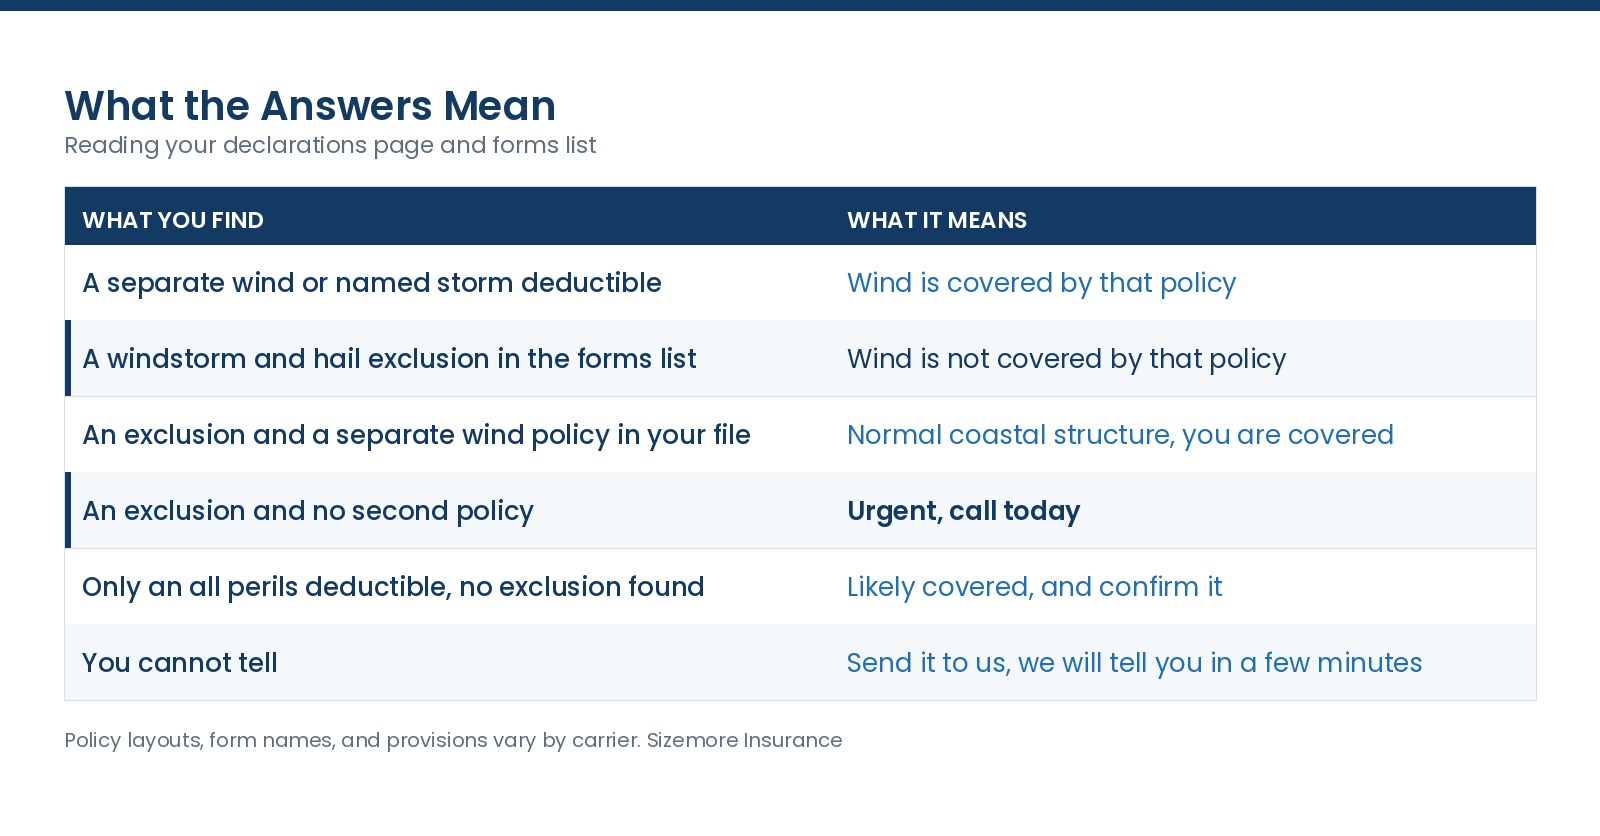
The takeaway: an exclusion with no second policy is the one answer that requires a phone call today rather than at renewal.
Policy layouts, form names, and provisions vary by carrier. Review your own documents.
Call us today. Not at renewal.
Do not wait for a storm to be named, because carriers restrict binding once a storm is in a defined area and coverage cannot be added in that window.
Expect the wind coverage to be a separate policy with its own carrier, its own deductible, and its own renewal date.
Expect a percentage deductible on a coastal property, and calculate it in dollars.
Confirm liability sits somewhere, because a wind-only policy generally carries none.
A quote that came in unusually low is the usual signal. If a coastal quote was noticeably cheaper than the others, a wind exclusion is a common reason.
A policy change at renewal can add an exclusion without a conversation. Read the forms list every year, not just at the beginning.
Commercial property works the same way, with the same structures and the same exclusion language.
A condominium unit owner has a different version of this question, because wind may be excluded from the association's master policy rather than from yours.
A boat policy has its own named storm structure, separate from the house.
Buying a coastal property is the moment to ask, during due diligence, because insurability affects what the property costs to own.
How do I know if wind is covered?
Look for a separate wind or named storm deductible on the declarations page, and read the forms list for a windstorm and hail exclusion.
Where exactly is the exclusion?
In the endorsement or forms list, usually the last pages of the policy.
What if I cannot tell?
Send us the declarations page and the forms list. It takes a few minutes.
What if wind is excluded and I have no other policy?
Call today. That is the loss most likely to happen and it is uncovered.
Can I add it when a storm is coming?
Generally not. Carriers restrict binding once a storm is in a defined area.
Does this apply to my commercial building too?
Yes, with the same structures and the same exclusion language.
We have been an independent insurance company in North Carolina since 1977. Send us your declarations page and forms list and we will answer this in a few minutes. Insurance made just for you.
Policy layouts, form names, exclusions, and binding restrictions vary by carrier and are subject to change. Review your own policy or talk to your advisor.