Two things about your belongings coverage, and the second one is where people get surprised.
Many people underestimate what they own, and not by a little.
Walk each room and add it up. Not what you paid, what it would cost to replace today.
The kitchen alone is small appliances, cookware, dishes, and everything in the drawers.
Clothes are the category people leave out entirely, and replacing a full wardrobe is a real number.
Electronics, including the things that are not obvious. Chargers, monitors, a router, headphones, a game console.
Furniture, including the pieces you inherited or found, because you still have to replace them with something.
Everything in closets and storage, which is where the forgotten value lives.
The exercise takes twenty minutes and it frequently produces a number well above the limit someone would have guessed at.
Your policy has a total limit, and certain categories have their own lower limit inside it.
You can have a substantial personal property limit and still recover a small amount on the category that mattered.
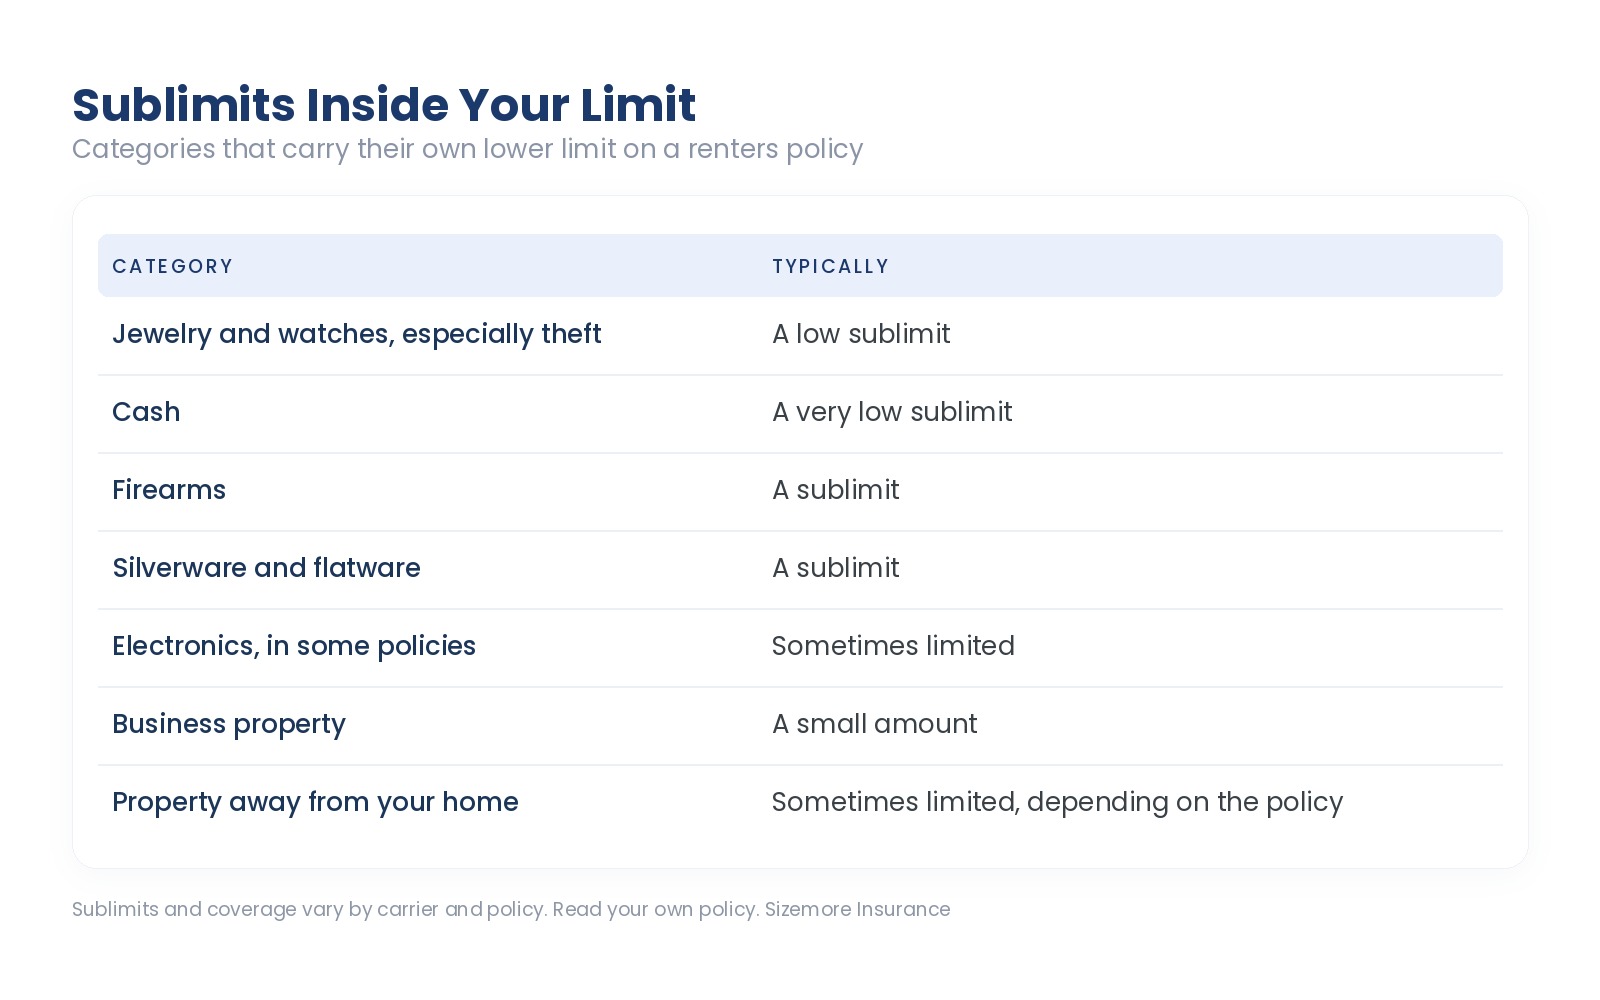
The takeaway: an engagement ring is the classic example. A stolen ring can produce a payment far below what the ring is worth, no matter how high your overall limit is.
Sublimits and coverage vary by carrier and policy. Read your own policy.
The fix is scheduling, sometimes called a personal articles floater or scheduled personal property.
You list the specific item, with a value and usually an appraisal or a receipt.
It comes out from under the sublimit and is covered at the scheduled amount.
Coverage is frequently broader, including things a base policy will not cover, like losing a stone out of a ring or simply misplacing an item, depending on the form.
Frequently no deductible applies, which matters on a smaller item.
What is worth scheduling for a renter:
It generally costs little relative to the item, and it is one of the most useful adjustments many renters can make to their policy.
Appraisals are frequently required above a value threshold, and they should be current.
Business property has a small limit on a renters policy, which matters if you work from home. That has its own article.
Property away from home is generally covered, though some policies limit the amount, including for things in a storage unit or at a second residence.
Roommate belongings are not covered unless they are named on your policy.
Named perils versus open perils affects what causes of loss apply. Ask which yours is.
Receipts and photographs are what prove a claim, and documenting your belongings has its own article.
How much personal property coverage do I need?
Walk each room and add up replacement costs. It is frequently more than people guess.
What is a sublimit?
A lower limit that applies to a specific category inside your overall limit, like jewelry or cash.
Why would my ring not be fully covered?
Jewelry sublimits, particularly for theft, are frequently low regardless of your total limit.
How do I fix that?
Schedule the item. It comes out from under the sublimit, coverage is frequently broader, and it generally costs little.
Do I need an appraisal?
Frequently above a value threshold, and it should be current.
Is my stuff covered in a storage unit?
Generally yes, and some policies limit the amount. Ask what yours says.
Sizemore Insurance is an independent insurance company founded in North Carolina in 1977, writing in both North Carolina and South Carolina. Tell us what you own that would be hard to replace and we will tell you what should be scheduled. Insurance made just for you.
Coverage, sublimits, and provisions vary by carrier and policy and are subject to change. Nothing here is a coverage determination. Review your own policy or talk to your advisor.