Many renters policies start at a base liability limit, and many people never look at it.
Raising it is among the least expensive things you can do to your insurance, and it is the part of the policy that reaches beyond your belongings into everything else you have and will have.
Injury to someone else that you are responsible for. A guest falls, your dog bites, something happens in your place.
Damage to someone else’s property. A fire you caused. Water that reached the apartment below. A neighbor’s belongings.
Your legal defense, which is generally in addition to the limit and which matters because defending a claim that pays nothing still costs real money.
And it follows you. Liability coverage generally applies to things you are responsible for away from your home too, not just inside the apartment.
A serious injury claim involving medical bills, lost income, and non-economic damages can go past a base limit quickly.
Building damage from a fire you caused is not a furniture-sized number. Repairing units in an apartment building is a real figure and your landlord’s insurer can pursue it.
And you have more to protect than you think. Not just what you own now. A judgment can last for years and reach assets you build later, which for someone early in their career is the thing actually at risk.
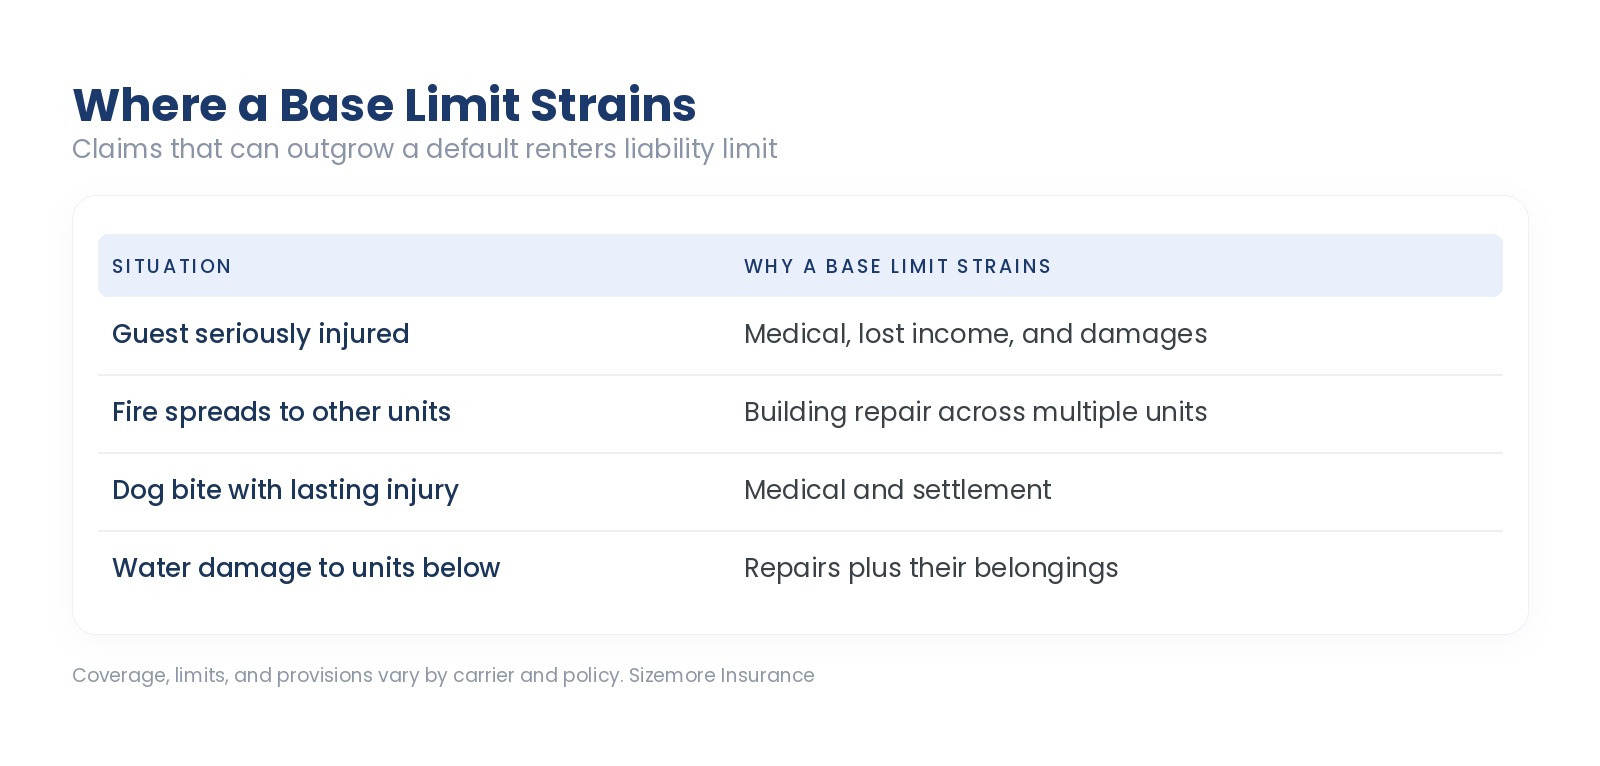
The takeaway: the limit that matters is not what your stuff is worth, it is what a claim against you could be worth.
Coverage, limits, and provisions vary by carrier and policy.
Start above the base. Ask what the next tier up costs. It is frequently a small monthly difference.
Think about your trajectory, not just your current assets. A judgment can follow you for years and reach what you build later.
Consider an umbrella if you have real assets, a higher income, a dog, or anything that raises your exposure. A personal umbrella sits above your renters and auto liability and it is relatively inexpensive for the limit.
Match it to your auto liability, because an umbrella requires stated underlying limits on both and mismatched limits complicate it.
Tell us about the dog, the pool access, the trampoline, or anything else that changes the picture. Some of those affect eligibility rather than price.
How much renters liability do I need?
More than the base limit. Ask what the next tier costs, because it is frequently small.
What does it cover?
Injury to others and damage to their property that you are responsible for, plus your defense.
Does it follow me outside my apartment?
Generally yes, for things you are responsible for.
Do I need an umbrella as a renter?
If you have assets, a strong income trajectory, or a dog, it is worth pricing. It is relatively inexpensive for the limit.
Does my dog affect it?
Some breeds and any bite history can affect eligibility or coverage. Disclose it.
What if my landlord requires a specific limit?
Tell us the number and we will set it there or higher.
Sizemore Insurance is an independent insurance company founded in North Carolina in 1977, writing in both North Carolina and South Carolina. Tell us what you do, what you own, and whether you have a dog and we will set the limit properly. Insurance made just for you.
Coverage, limits, eligibility, and provisions vary by carrier and policy and are subject to change. Nothing here is a coverage determination or legal advice. Review your own policy or talk to your advisor.