Less than people expect, and that is the honest headline.
Renters insurance is one of the least expensive policies most people will ever buy, and the difference between a good one and a cheap one is frequently a small monthly amount.
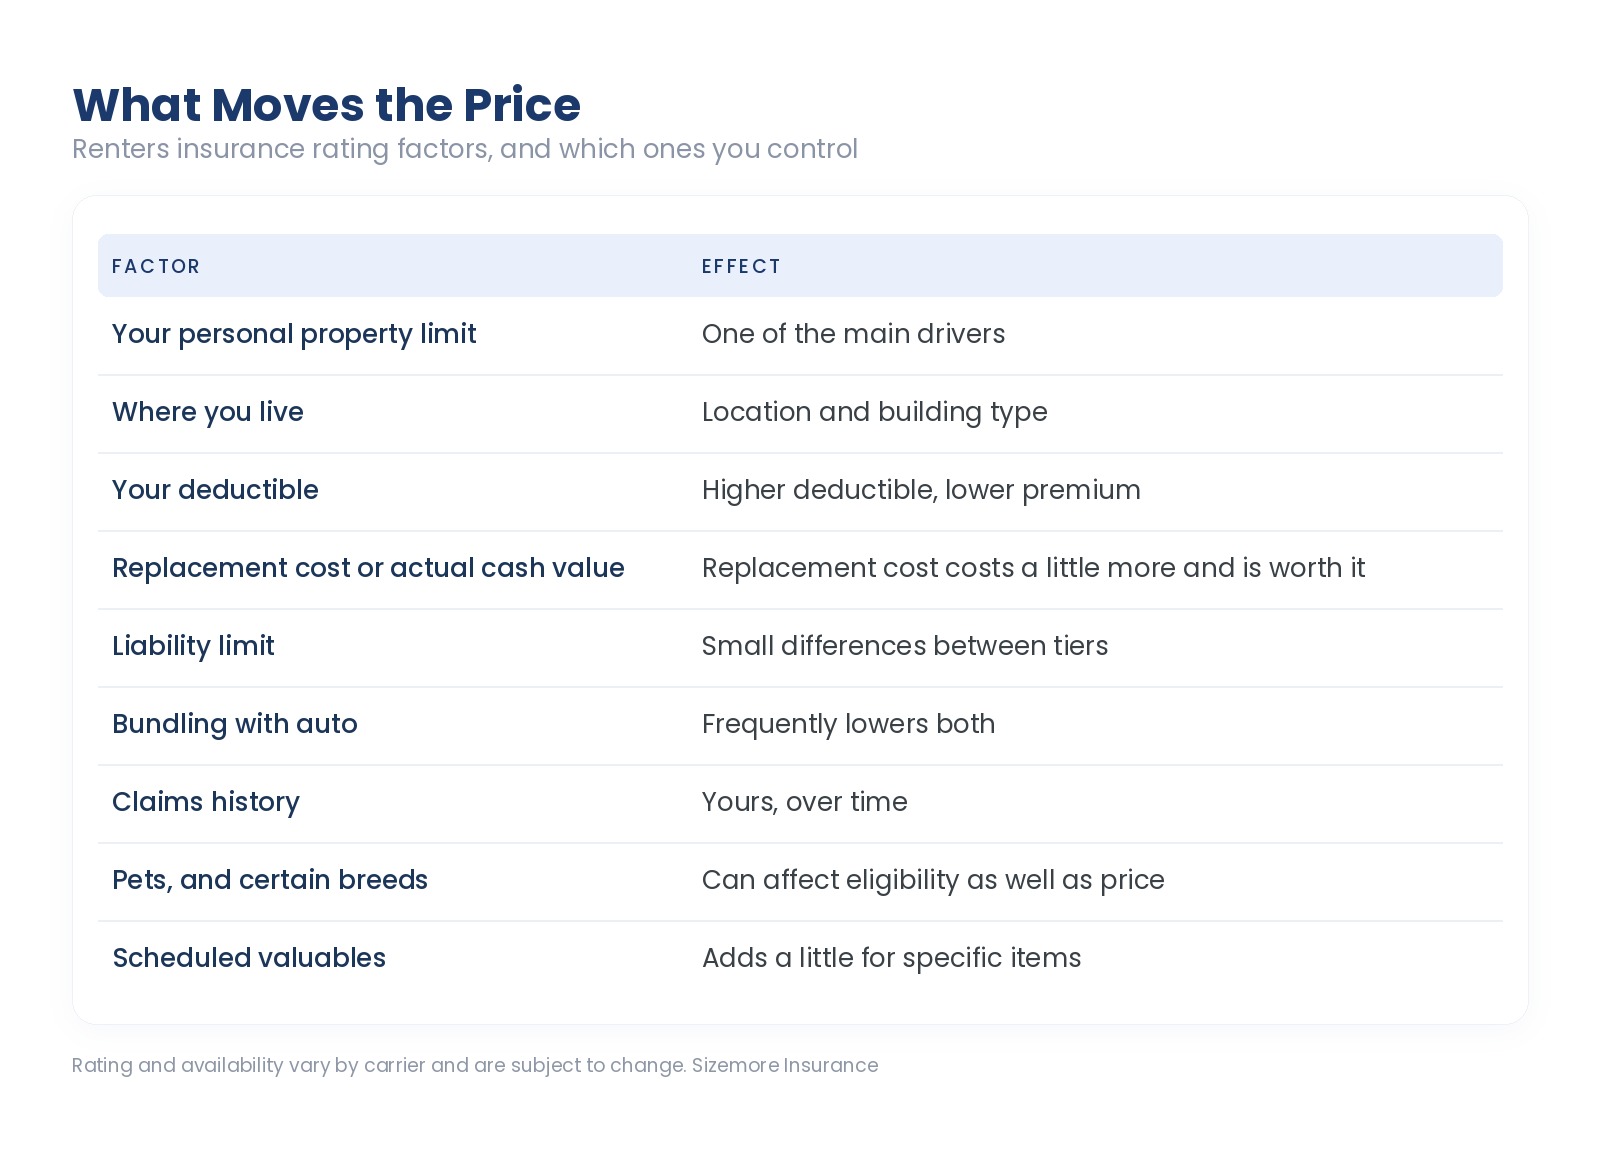
The takeaway: bundling with auto is frequently the largest single saving available and it lowers the auto side too.
Rating and availability vary by carrier and are subject to change. Get a quote for your situation.
If you have auto insurance and no renters policy, ask what both together cost.
Frequently the discount on the auto side offsets much of the renters premium, because the multi-policy discount applies to the larger premium.
That makes renters insurance one of the better values in personal insurance, and it is the most useful thing in this article.
Replacement cost. The difference is small and it changes what a claim pays. Its own article covers why.
The liability limit. One of the least expensive parts of the policy and the part that reaches furthest.
The personal property limit. Many people set this too low because they underestimate what they own. Walk each room and add it up.
Scheduled valuables, if you have a ring, a good laptop, a bike, or an instrument. Those hit sublimits and scheduling is generally inexpensive.
Underbuying the property limit is one of the most common. A base limit chosen without adding anything up is frequently short.
Setting a very low deductible frequently costs more monthly than it is worth on a policy this size, and small claims are not worth filing anyway.
Buying through a link at lease signing without comparing. It is convenient and it is frequently a minimum policy that meets the lease requirement and not much else.
Not bundling, which is money left on the table.
How much does renters insurance cost?
Less than most people expect, and it depends on your limits, deductible, location, and whether you bundle. Ask for a quote.
What is the biggest way to save?
Bundling with auto, which frequently lowers both.
Should I raise my deductible?
Somewhat, since small claims are not worth filing. Not so high that a real claim hurts.
Is the cheapest policy fine?
It is frequently actual cash value with a low property limit and a base liability limit. The upgrade generally costs little.
Does a pet change the price?
It can, and some breeds affect eligibility rather than price. Disclose it.
What if my landlord requires a specific limit?
Tell us the number and we will meet or exceed it.
Sizemore Insurance is an independent insurance company founded in North Carolina in 1977, writing in both North Carolina and South Carolina. Tell us where you live and whether you have auto with anyone and we will show you both numbers. Insurance made just for you.
Rating, availability, and discounts vary by carrier and are subject to change. Review your own situation with your advisor.