
Coastal wind is written largely the same way on a house and on a commercial building. Similar exclusions, the same residual mechanisms, the same percentage deductible structures.
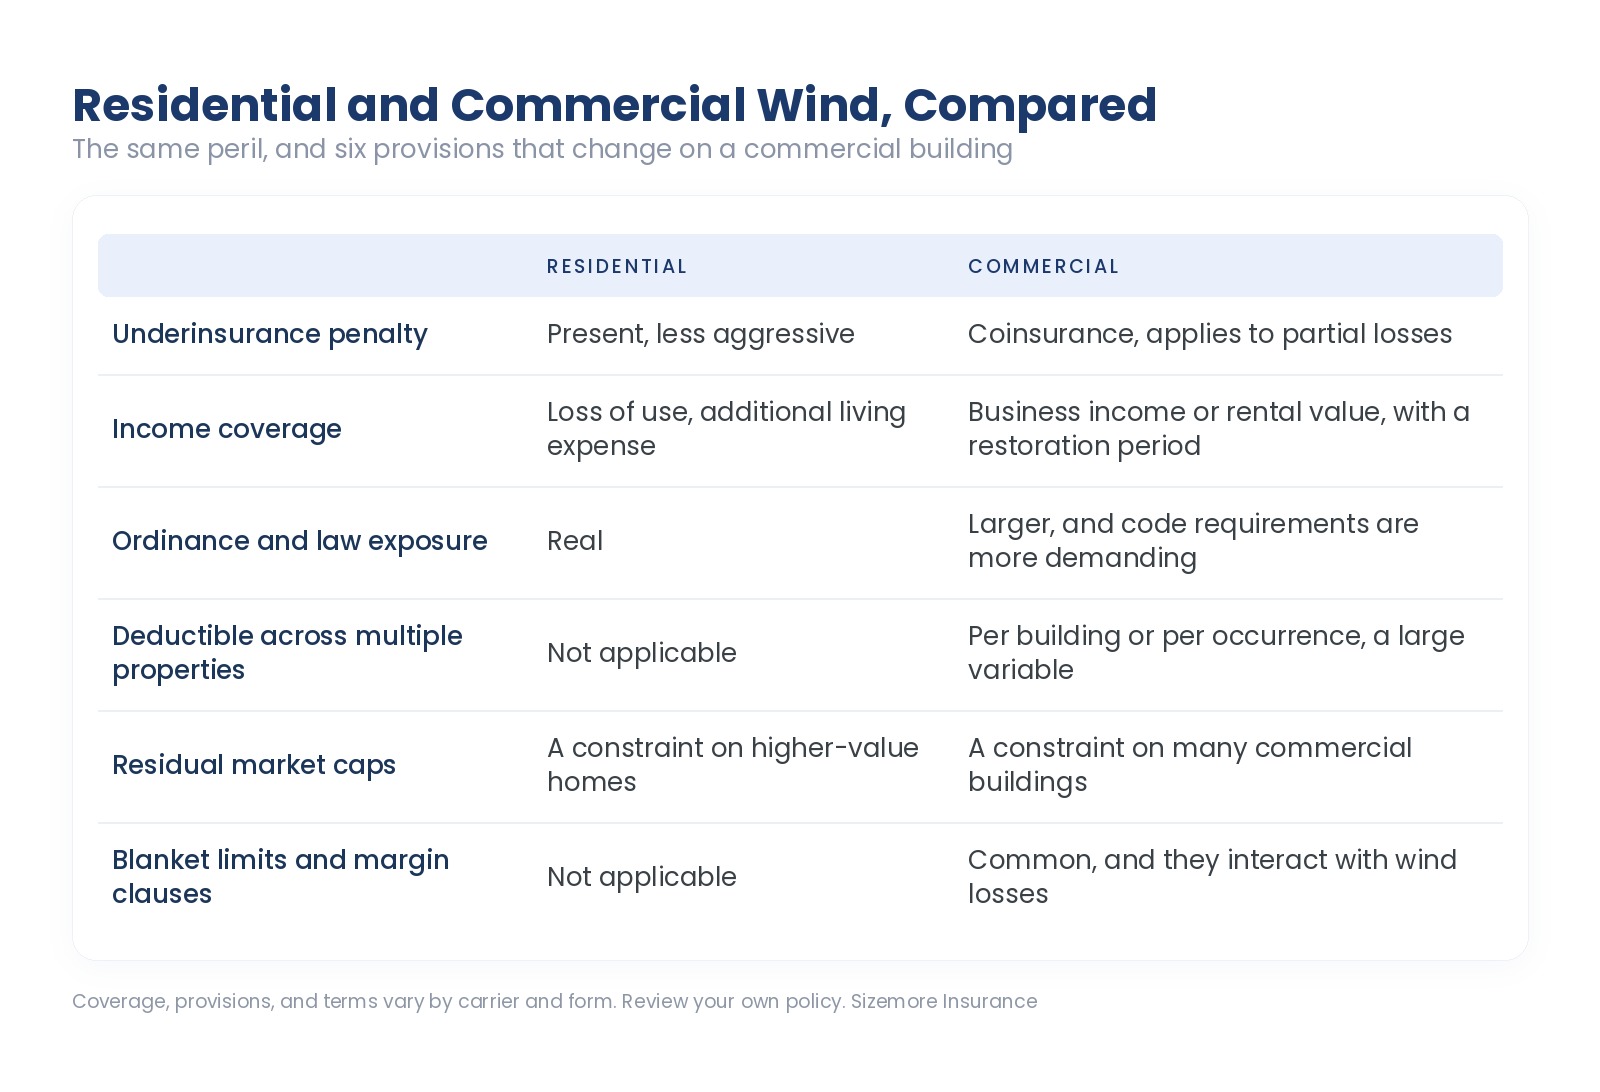
Four things differ substantially, and each one makes the commercial version harder to get right.
Coinsurance. Commercial property policies condition replacement cost settlement on carrying a stated percentage of full value, commonly 80, 90, or 100 percent. Fall below it and the policy reduces claims proportionally, including partial ones. Residential policies have a version of this and it is less aggressive. On a wind claim, an underinsured commercial building gets reduced twice: once by coinsurance and again by the percentage deductible.
Business income versus loss of use. A homeowner’s loss of use pays the additional cost of living elsewhere. A commercial owner’s business income or rental value coverage replaces revenue, runs on a defined period of restoration, and frequently carries its own coinsurance. It is a more complex coverage and it is more often sized wrong.
Ordinance and law. Both need it and the commercial exposure is larger, because commercial code requirements around sprinklers, egress, accessibility, and separation are more demanding than residential ones, and many commercial buildings predate current code.
Deductible application across a schedule. On a portfolio, the percentage may apply per building or per occurrence. A storm touching four properties can produce four deductibles under one structure and one under another. That distinction does not exist for a single-family homeowner and it can be worth several hundred thousand dollars.
The takeaway: the same storm on a commercial building runs through more provisions, and each one can reduce the recovery.
Coverage, provisions, and terms vary by carrier and form. Review your own policy.
Valuation matters more. On a house, an inaccurate limit is a problem at a total loss and a modest one on a partial loss. On a commercial building, coinsurance makes it a problem on every claim.
Income coverage needs actual work. A rent roll, a realistic restoration period, and an extended period of indemnity. A default limit set at acquisition is frequently short.
The residual market cap binds more often, because commercial building values more commonly exceed it, which makes excess wind layering more routine on the commercial side.
Blanket programs interact with wind losses. A margin clause capping recovery at a percentage of a building’s reported value reintroduces the underinsurance problem inside a blanket structure.
Mixed-use buildings sit between the two, and the residential component frequently determines which market will write the property at all.
A residential rental is treated more like a business, written on a dwelling policy rather than a homeowners policy, which changes the income coverage and the settlement provisions.
Tenant improvements raise a question on the commercial side that does not exist residentially: whose coverage rebuilds the buildout after a wind loss.
Ordinance and law has a time element on the commercial side, extending income coverage when code-driven work extends the rebuild. That is separate from the increased cost of construction and it is frequently omitted.
Lender requirements are more specific on commercial loans, including deductible caps that a percentage storm deductible can exceed.
Mitigation credits are developing on both sides, and the April 2026 dwelling rate settlement built credits for fortified construction into many eastern North Carolina territories.
Is wind coverage different on a commercial building?
The structure is the same and four things differ: coinsurance, income coverage, ordinance and law exposure, and how the deductible applies across multiple buildings.
What is coinsurance and why does it matter on a wind claim?
It requires you to insure to a stated percentage of full value. Below that, claims are reduced proportionally, including partial ones, on top of the deductible.
Does the deductible apply per building?
It depends on the form. On a portfolio this is one of the largest variables in the structure.
Do I need ordinance and law on a commercial building?
On anything predating current code, in practical terms yes. The commercial code exposure is larger.
Is my income coverage adequate?
Compare the limit to your current rent roll and the period to a realistic rebuild. Many are short.
Do mitigation credits apply commercially?
Carrier by carrier. The recent North Carolina rate settlement credits apply to dwelling policies, and commercial carriers price mitigation their own way.
Sizemore Insurance is an independent insurance company founded in North Carolina in 1977, writing in both North Carolina and South Carolina. Send us your declarations page and your rent roll and we will run the wind exposure through every provision that touches it. Insurance made just for you.
Coverage, provisions, credits, and terms vary by carrier and form and are subject to change. Review your own policy or talk to your advisor.