

The center console is the boat of this coast. Beaufort, Wrightsville, Southport, Hatteras, Morehead. A twin or triple outboard boat that fishes inshore in the spring and runs to the Gulf Stream in the summer.
Two things about that pattern matter to a policy, and both are things owners rarely check until it is too late.
This is the first thing to look at.
Your policy defines the geographic area it covers. A boat rated for inland and coastal waters within a stated distance from shore is not covered beyond it.
If you run to the break, to the Gulf Stream, or to a wreck fifty miles out, the policy has to contemplate it. Many do not by default, and adding offshore navigation is generally available and priced accordingly.
Read the limits before you plan the trip. A boat sixty miles out on a policy written for twenty is not a technicality, and it is the situation where you most need the coverage to work.
Also check whether the limits change seasonally, whether they contemplate running to Bermuda or the Bahamas if you would ever consider it, and whether a delivery under someone else's operation is addressed.
An offshore center console carries a substantial value in electronics that the hull value does not reflect.
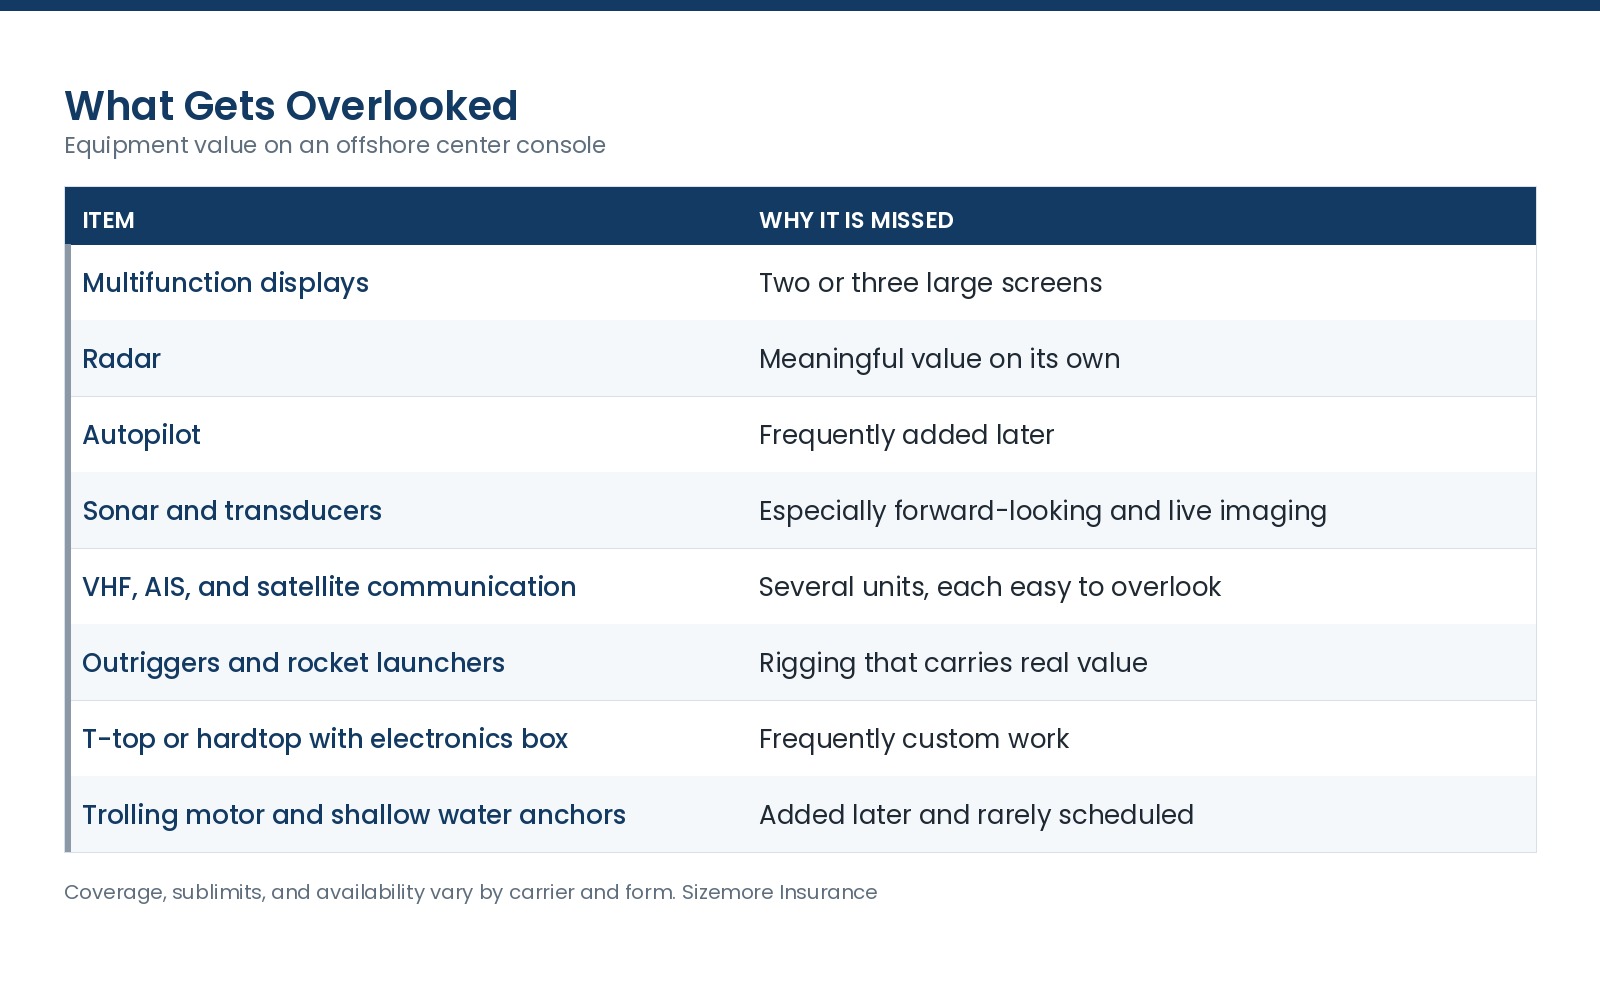
The takeaway: a boat that sold at one price frequently has tens of thousands of dollars of equipment added to it, and a stock valuation does not include any of it.
Coverage, sublimits, and availability vary by carrier and form. Review your own policy.
Schedule it with receipts and photographs, and update the schedule when you add more.
A repower changes the value substantially and it is one of the most commonly unreported changes on this kind of boat. New outboards on an older hull can be worth more than the hull.
Named storm deductibles apply on the coast, frequently as a percentage of insured value.
Wreck removal and pollution liability matter more offshore, because recovery is harder and fuel capacity is larger.
Towing limits should reflect the distance you run. A tow from thirty miles out is not a routine tow, and a modest towing limit will not reach it.
Tournament fishing may raise questions, including whether the policy contemplates it and whether prize or entry exposure is addressed. Ask before you enter.
Chartering the boat, even occasionally, is a commercial use outside a personal policy.
Agreed value matters here, because a well-equipped older hull with new power is exactly the kind of boat an after-the-fact valuation undervalues.
Does my policy cover me offshore?
Only within your navigation limits. Read them and extend them if you run beyond.
Are my electronics covered?
Permanently installed equipment generally is, and aftermarket units may be sublimited. Schedule them.
Do I need to report a repower?
Yes. It changes the value substantially and it is one of the most commonly missed updates.
What if I need a tow from thirty miles out?
Check your towing limit, because a modest one will not cover it.
Can I fish tournaments on this policy?
Ask, because policies vary on how they treat it.
Should I be on agreed value?
On a well-equipped boat with new power, yes.
We have been an independent insurance company in North Carolina since 1977, on a coast full of these boats. Tell us where you run and what is on it and we will build the policy around that. Insurance made just for you.
Coverage, navigation limits, sublimits, and availability vary by carrier and form. Review your own policy or talk to your advisor.