

Hull and machinery is the physical damage coverage on a boat policy. The hull, the motor, the permanently attached equipment, and generally the trailer if it is on the policy.
What it covers is straightforward. Where it stops is what decides claims, and marine exclusions are different from the ones on a car.
Whether the form is written as all risk with exclusions or as named perils varies, and all risk is broader and generally what you want.
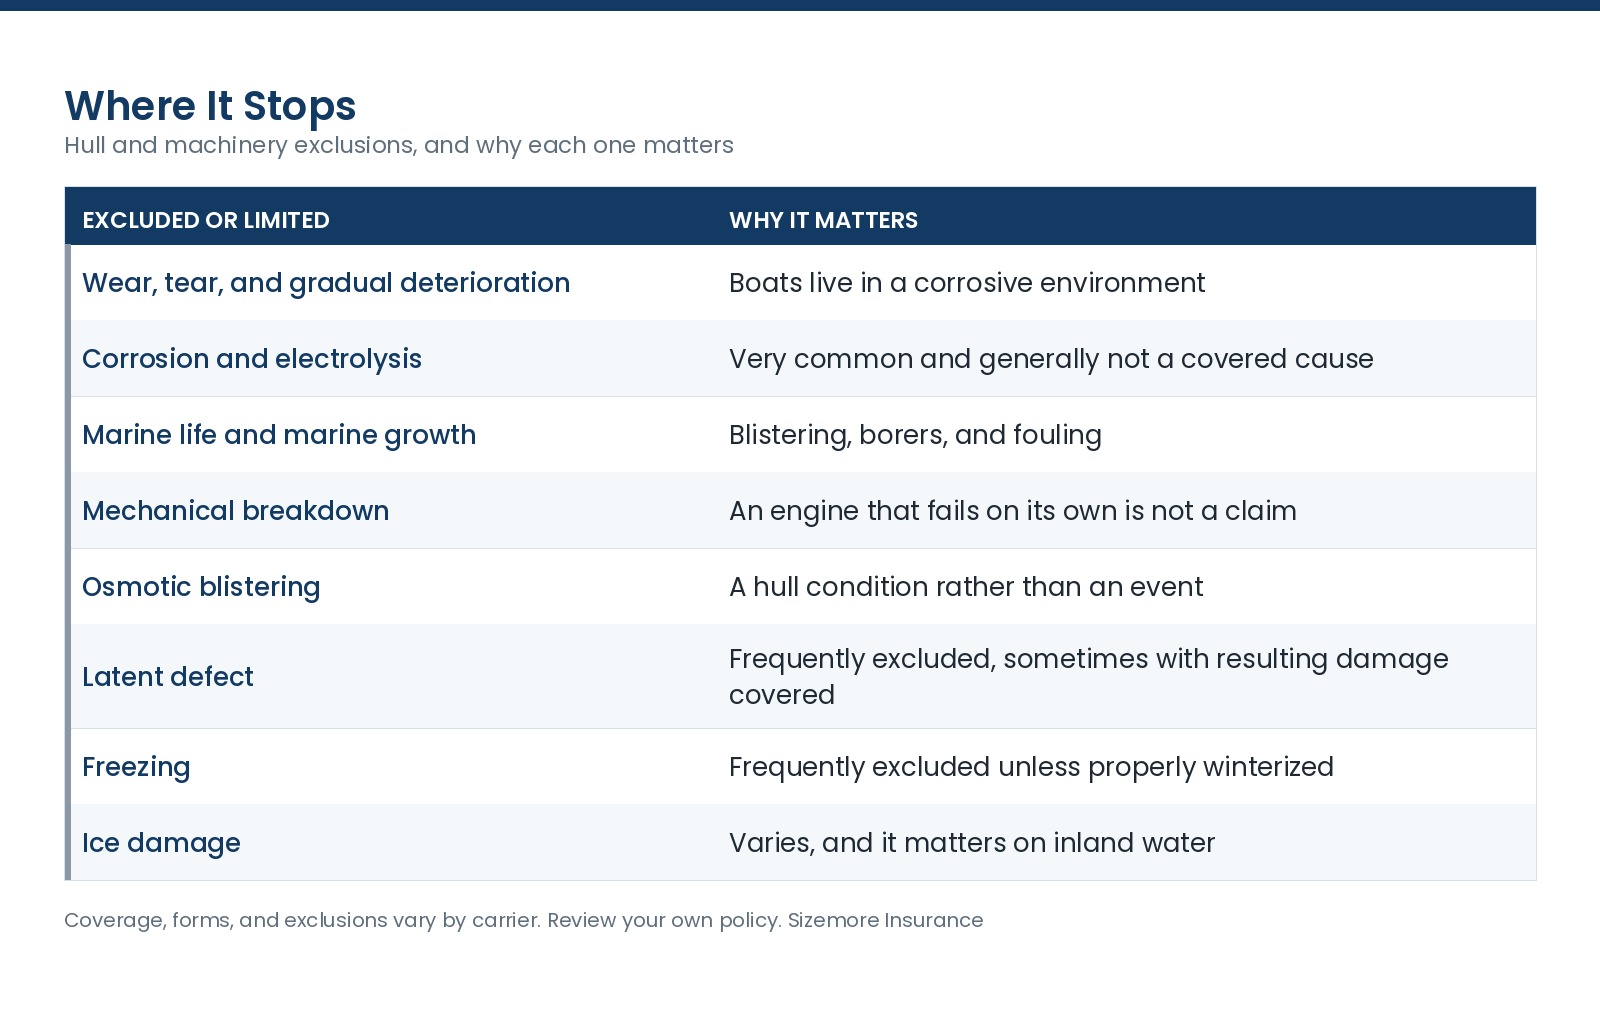
The takeaway: the exclusions are about condition and maintenance, and the coverage is about events. That distinction produces most of the disputes.
Coverage, forms, and exclusions vary by carrier. Review your own policy.
This is the one worth understanding.
Many marine policies exclude the failed part while covering the damage it causes. An old hose fails, and the hose is not covered, and the water damage from the flooding may be.
Some policies go further and exclude the resulting damage too, particularly where the cause was wear or corrosion. That is a meaningful difference between two policies that look similar on price, and it is worth asking about specifically.
Freezing is the version of this that catches Carolina owners. A vessel not properly winterized that suffers freeze damage frequently finds an exclusion. If you leave a boat in the water or on a trailer through winter, know what your policy requires.
The valuation basis governs the payout. Agreed value or actual cash value decides what a total loss pays, and it can affect how parts are settled on a partial loss.
Deductibles vary by cause. A flat deductible for ordinary claims and a percentage deductible for named storms is common on coastal policies.
Electronics may be sublimited, particularly aftermarket units. Schedule them if they are meaningful.
A survey may be required on older vessels, and its findings can become conditions.
Lay-up periods reduce coverage during a defined off season.
Navigation limits define where the coverage applies. Running outside them is a coverage question, not just a rules question.
Maintenance records matter, because where a carrier is weighing an event against a condition, documentation is what supports your position.
What does hull and machinery cover?
Physical damage to the vessel, motor, and permanently attached equipment from covered causes.
Is engine failure covered?
Mechanical breakdown is generally excluded. A sudden covered event that damages the engine is different.
Is corrosion covered?
Generally not. It is a condition rather than an event.
What about freeze damage?
Frequently excluded unless the vessel was properly winterized. Know what your policy requires.
Are my electronics covered?
Permanently installed equipment generally is, and aftermarket units may be sublimited. Ask, and schedule if needed.
Does it cover the trailer?
Frequently, if the trailer is on the policy. Confirm it.
We have been an independent insurance company in North Carolina since 1977. Send us your declarations page and we will tell you which form you are on and where it stops. Insurance made just for you.
Coverage, forms, exclusions, and provisions vary by carrier. Nothing here is a coverage determination. Review your own policy or talk to your advisor.