

Many boat owners have never thought about this one, and it is the coverage that turns a bad day into a genuinely expensive one.
A fuel release from a vessel triggers cleanup obligations under federal law. That applies to a sunken boat leaking fuel in a slip, an overflow at the fuel dock, a ruptured tank after a grounding, and a bilge discharge.
The obligation attaches to the owner, and the size of the release does not have to be large for it to be a reportable event.
A sinking. A vessel on the bottom with fuel aboard releases it. This is the common version and it happens most after storms.
A grounding that ruptures a tank or fuel line.
Fuel dock overfill, which is more common than people think and produces a visible sheen immediately.
A failed fitting, hose, or tank releasing into the bilge and then overboard.
A collision breaching a tank.
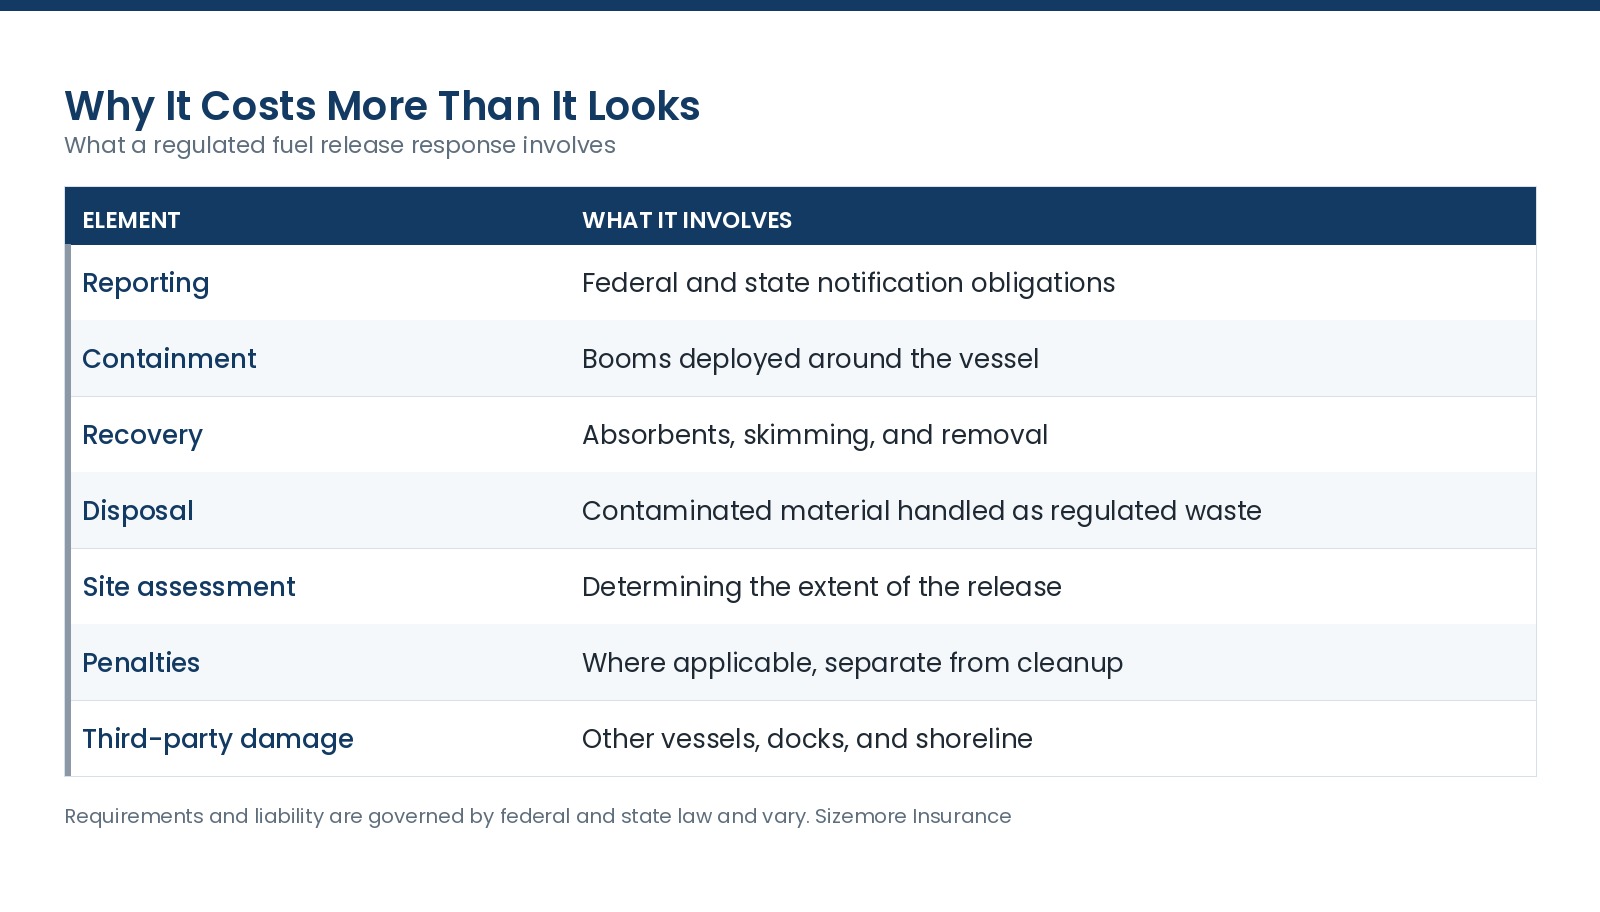
The takeaway: the response is regulated and specialized, and the cost reflects that rather than the volume of fuel.
Requirements and liability are governed by federal and state law and vary. Nothing here is legal advice.
Some policies include a pollution liability limit, frequently modest.
Some offer a higher separate limit, which is better on a larger vessel or one kept in the water.
Some do not address it clearly, which is the situation to identify.
Ask whether it is on the policy, what the limit is, and whether it covers cleanup costs, third-party damage, and defense.
The limit matters more on a vessel with meaningful fuel capacity or one kept in a slip, because those are where a release is most likely and most visible.
It travels with wreck removal. A sunken vessel produces both obligations at once, and a policy strong on one and silent on the other leaves a real gap.
Reporting obligations are prompt. A release generally has to be reported quickly, and delay is its own problem.
Marina contracts frequently address it, obligating the owner and holding the marina harmless. Read the slip agreement.
Prevention is inexpensive. An automatic bilge pump with a float switch, a fuel-air separator or vent filter, an absorbent bilge pad, and not topping off at the fuel dock all prevent the ordinary versions.
A bilge discharge counts. Pumping oily bilge water overboard is a release, and it is one owners do casually without thinking about it.
Older fuel systems are the usual cause of the non-storm version. Hoses, fittings, and tanks age.
Do not attempt cleanup yourself beyond containment. Regulated response is regulated for a reason and improvised cleanup can make the situation worse.
Does my boat policy cover a fuel spill?
Many include a pollution liability limit and it varies. Check for it specifically and check the amount.
How much coverage do I need?
More on a vessel with meaningful fuel capacity or one kept in the water. Ask what limits are available.
What do I do if it happens?
Contain what you safely can, report it promptly to the appropriate authority, and call your carrier. Do not attempt a full cleanup yourself.
Is a small sheen a problem?
It can be a reportable event. Size is not the only factor.
Does this come up in storms?
Frequently, because a sunken vessel releases fuel and produces removal and pollution obligations together.
How do I prevent the ordinary version?
A working bilge pump with a float switch, absorbent bilge pads, maintained fuel systems, and not overfilling at the dock.
We have been an independent insurance company in North Carolina since 1977. Send us your declarations page and we will tell you whether this coverage is on it and at what limit. Insurance made just for you.
Coverage, limits, and regulatory obligations vary by carrier, form, and jurisdiction and are governed by federal and state law. Nothing here is legal advice. Review your own policy or talk to your advisor.