

A ticket and an at-fault accident both raise your rate, and they get there differently.
A ticket produces a conviction, which is a fact on a court record. An at-fault accident produces a determination made by insurance companies about who caused it, and that determination is contestable in a way a conviction is not.
That difference is worth understanding before you accept a fault finding.
Under the Safe Driver Incentive Plan, an at-fault accident generates points based on the severity of the outcome rather than on how the accident happened.
Bodily injury or death produces the highest point assignment.
Property damage above a defined threshold produces points.
Property damage below that threshold, with no bodily injury and no moving violation conviction attached, may produce no points at all.
That last one matters and many drivers do not know it. A minor at-fault accident with modest damage and no citation can pass without a surcharge, depending on the numbers.
Point values and thresholds are set by the North Carolina Rate Bureau under Department of Insurance oversight and are subject to change. Ask your advisor what applies to your situation.
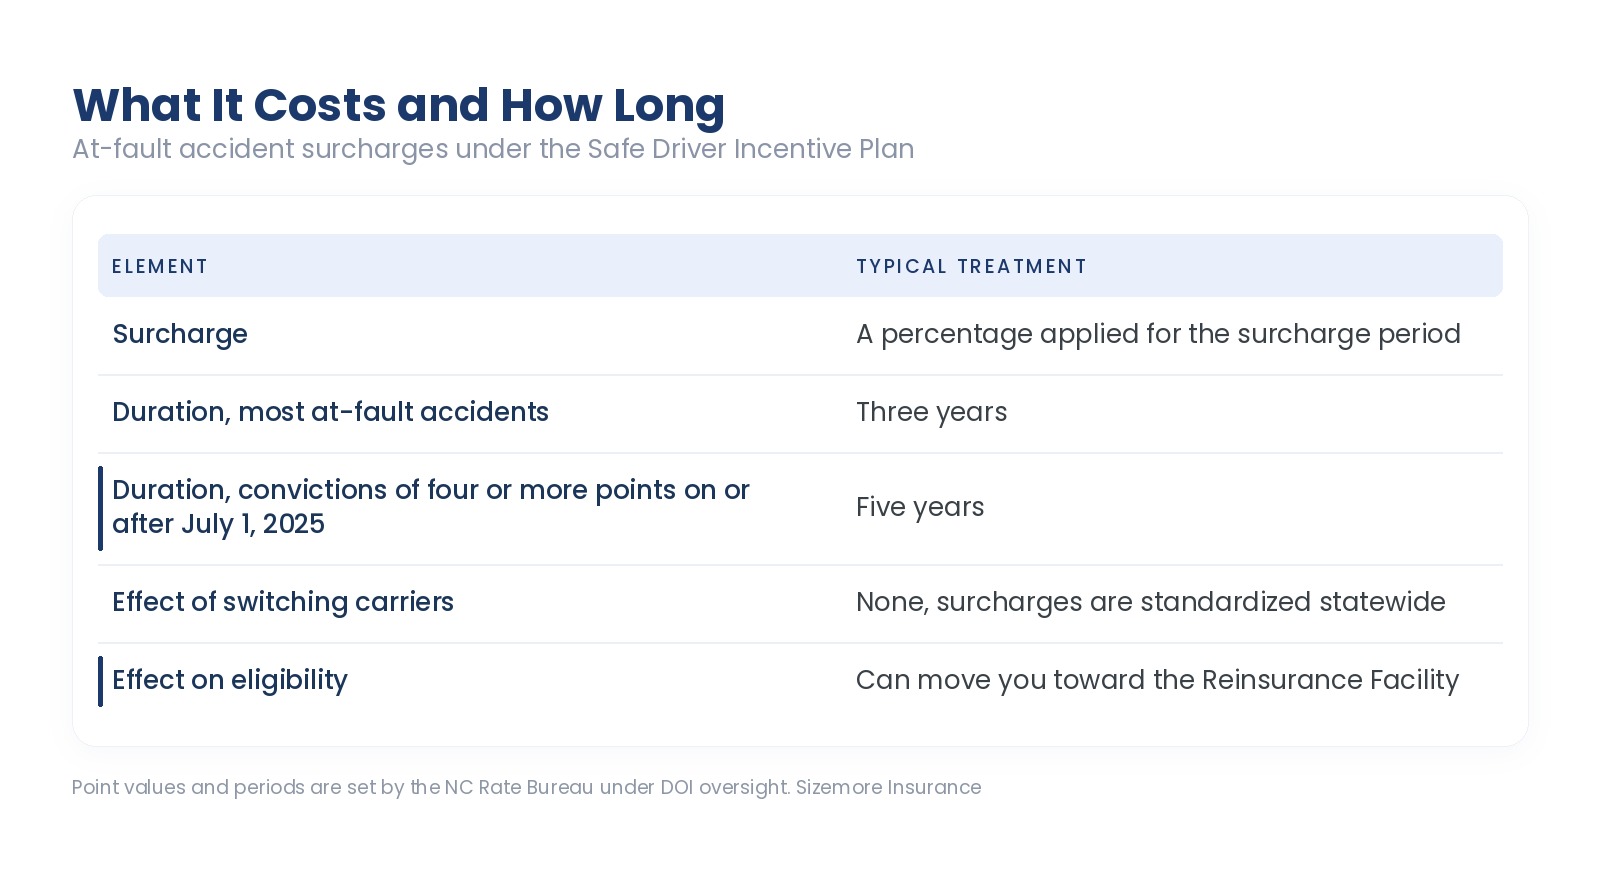
The takeaway: the surcharge follows the driver, not the company, and time is what removes it.
Confirm current surcharge factors and periods with your advisor.
In most states, partial fault reduces recovery. In North Carolina, contributory negligence means a claimant who contributed to their own injury may be barred from recovering from the at-fault party entirely.
That has two consequences for you.
If fault is disputed and it goes against you, you carry the surcharge and the liability. If it goes your way, the other party may recover nothing.
The facts decide it. Photographs, the police report, witness names, and what was said at the scene all matter more here than in a comparative negligence state.
Which is why conceding fault at the scene, or in a phone call afterward, is a decision with real consequences. Describe what happened. Do not characterize who was responsible.
Not-at-fault accidents do not generate points. Being hit by someone else is not a surcharge event, and reporting it is not the same as being blamed for it.
Accident forgiveness works differently here. Because SDIP surcharges are set by the state rather than by carriers, the accident forgiveness programs advertised nationally do not operate the same way in North Carolina. Ask specifically what a carrier is actually offering.
A comprehensive claim is not an at-fault accident. Hail, a deer strike, theft, or a tree falling on the car are comprehensive losses. No points.
Multiple claims still matter even without points. Frequency affects how a carrier views the account at renewal, separate from the surcharge.
A citation and an accident can produce both. An at-fault accident with a moving violation conviction attached can generate points from each.
Report it even if you are unsure. Late notice can jeopardize coverage, and reporting is not the same as filing a claim.
How long does an at-fault accident stay on my insurance in North Carolina?
Generally three years, and five for convictions assigned four or more points occurring on or after July 1, 2025.
Will switching companies remove the surcharge?
No. SDIP surcharges are standardized statewide. Switching can change your base rate.
Does a minor accident always cost me?
Not necessarily. Property damage below the applicable threshold with no injury and no citation may produce no points.
Does a not-at-fault accident raise my rate?
It should not generate SDIP points. Claim frequency can still affect renewal considerations.
Can I dispute a fault determination?
Yes. It is a determination rather than a conviction, and evidence matters. Tell us if you believe it is wrong.
Should I pay for minor damage myself to avoid a claim?
Sometimes. Compare the repair cost to your deductible and the likely surcharge, and call us before deciding.
Sizemore Insurance is an independent insurance company that has been placing coverage in North Carolina since 1977. Tell us what happened and we will tell you what it is likely to cost and for how long. Insurance made just for you.
Point values, thresholds, surcharge factors, and periods are set by the North Carolina Rate Bureau under Department of Insurance oversight and are subject to change. Nothing here is legal advice. Review your own policy or talk to your advisor.