
Plenty of people in this region drive in both states weekly and own property in both.
They assume the rules travel with them. Several do not, and one of the differences decides whether an injured person recovers anything at all.
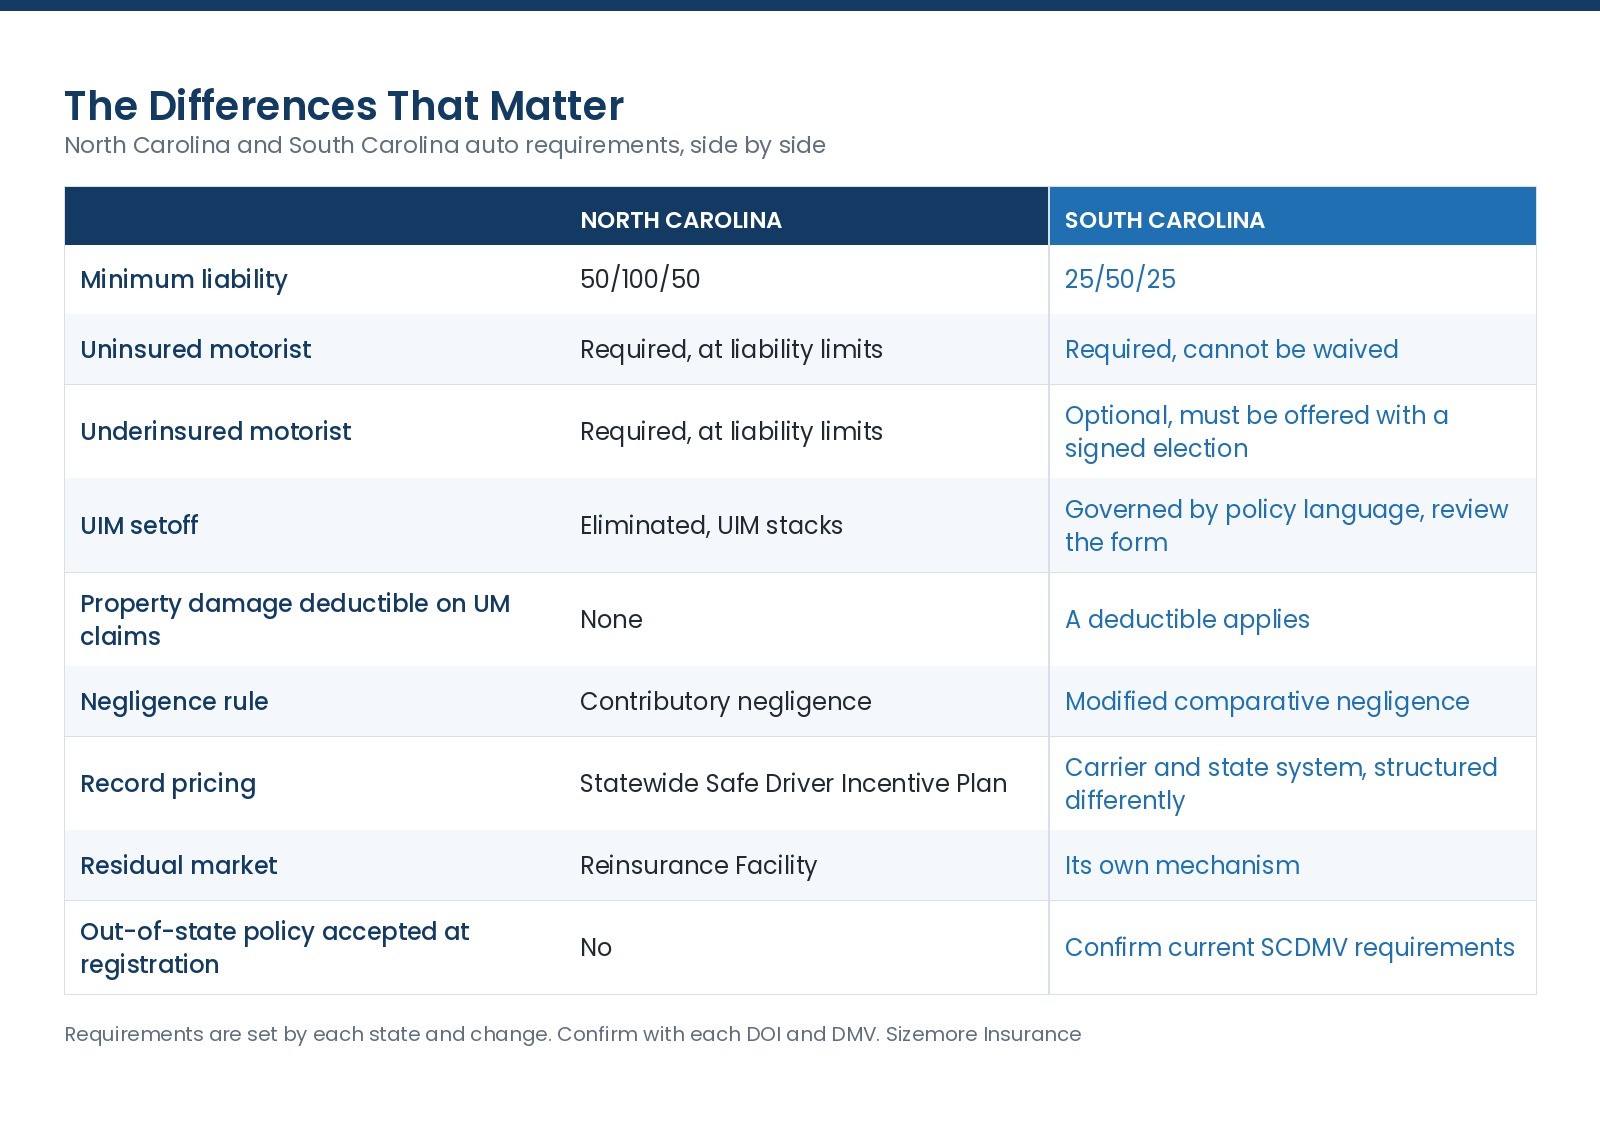
The takeaway: North Carolina requires roughly twice the minimum liability and mandates underinsured motorist coverage that South Carolina leaves optional.
Requirements are set by each state and change. Confirm current rules with each Department of Insurance and Department of Motor Vehicles.
This is the one that changes outcomes.
North Carolina applies contributory negligence. A claimant who contributed to their own injury, even slightly, may be barred from recovering from the at-fault party entirely.
South Carolina applies a modified comparative rule. Recovery is reduced by the claimant's share of fault and barred once that share passes a threshold.
The same accident, on the same facts, can produce a full defense verdict on one side of the line and a reduced recovery on the other.
For a driver, the practical consequence is that in North Carolina your own uninsured and underinsured motorist coverage carries more weight, because a disputed fault finding can leave you with nothing from the other side. That is a coverage decision rather than a legal one, and it is one you control.
North Carolina now requires underinsured motorist coverage at limits matching your liability, and since July 1, 2025 it stacks on top of the at-fault driver's payment rather than being reduced by it.
South Carolina treats it as an optional coverage that must be offered, with a signed election if you decline. That means a South Carolina driver can be carrying no underinsured motorist coverage at all and not remember declining it.
If you have a South Carolina policy, look for it on the declarations page. If it is not there, that is a conversation worth having.
Coverage follows the vehicle and the policy, not the driver. A North Carolina policy on your car generally covers you while driving it in South Carolina, and many policies contain provisions adjusting limits upward to meet another state's minimums where required. That is not the same as your coverage being ideal there.
Registering in North Carolina requires a policy from a company licensed here. Out-of-state policies are not accepted, which surprises people moving down from other states.
Two vehicles in two states is a real structure. A student at college in one state and a family in the other, or a second home, means garaging address questions that affect rating in both.
Record pricing does not translate. North Carolina's statewide surcharge system has no direct South Carolina counterpart, so a driver moving between them should expect their record to be priced differently.
South Carolina has its own arrangements for drivers who cannot obtain coverage in the standard market, including a residual mechanism. Confirm current structure with the Department of Insurance.
Umbrella coverage should reach both. If you own vehicles registered in each state, confirm every one is scheduled.
What is the minimum car insurance in South Carolina?
25/50/25 in liability, with uninsured motorist coverage required at those limits and not waivable.
Is underinsured motorist coverage required in South Carolina?
No. It must be offered, and declining it requires a signed election. Check your declarations page.
Does my North Carolina policy cover me in South Carolina?
Generally yes while driving, and many policies adjust to meet another state's minimums where required. It does not make your limits adequate there.
Which state is more expensive?
North Carolina requires substantially more coverage. Actual cost depends on territory, vehicle, and record, so compare quotes rather than assuming either direction.
What is the practical difference in a claim?
North Carolina's contributory negligence rule can bar recovery entirely where the claimant shares any fault. South Carolina reduces recovery instead.
I am moving. What do I do first?
Bind a policy with a carrier licensed in the state you are moving to. Registration and licensing both depend on it.
Sizemore Insurance is an independent insurance company that has served North Carolina since 1977 and writes in South Carolina as well. Send us both declarations pages and we will look at the whole position. Insurance made just for you.
Requirements, rules, and residual market structures are set by each state and are subject to change. Nothing here is legal advice. Confirm current requirements with each state's Department of Insurance and Department of Motor Vehicles, and review your own policy with your advisor.