This is one line on your policy and it decides what a claim actually pays you.
Replacement cost pays what it costs to buy the item new today.
Actual cash value pays what the item was worth, meaning the cost to replace it minus depreciation for age and use.
Same policy, same limit, very different check.
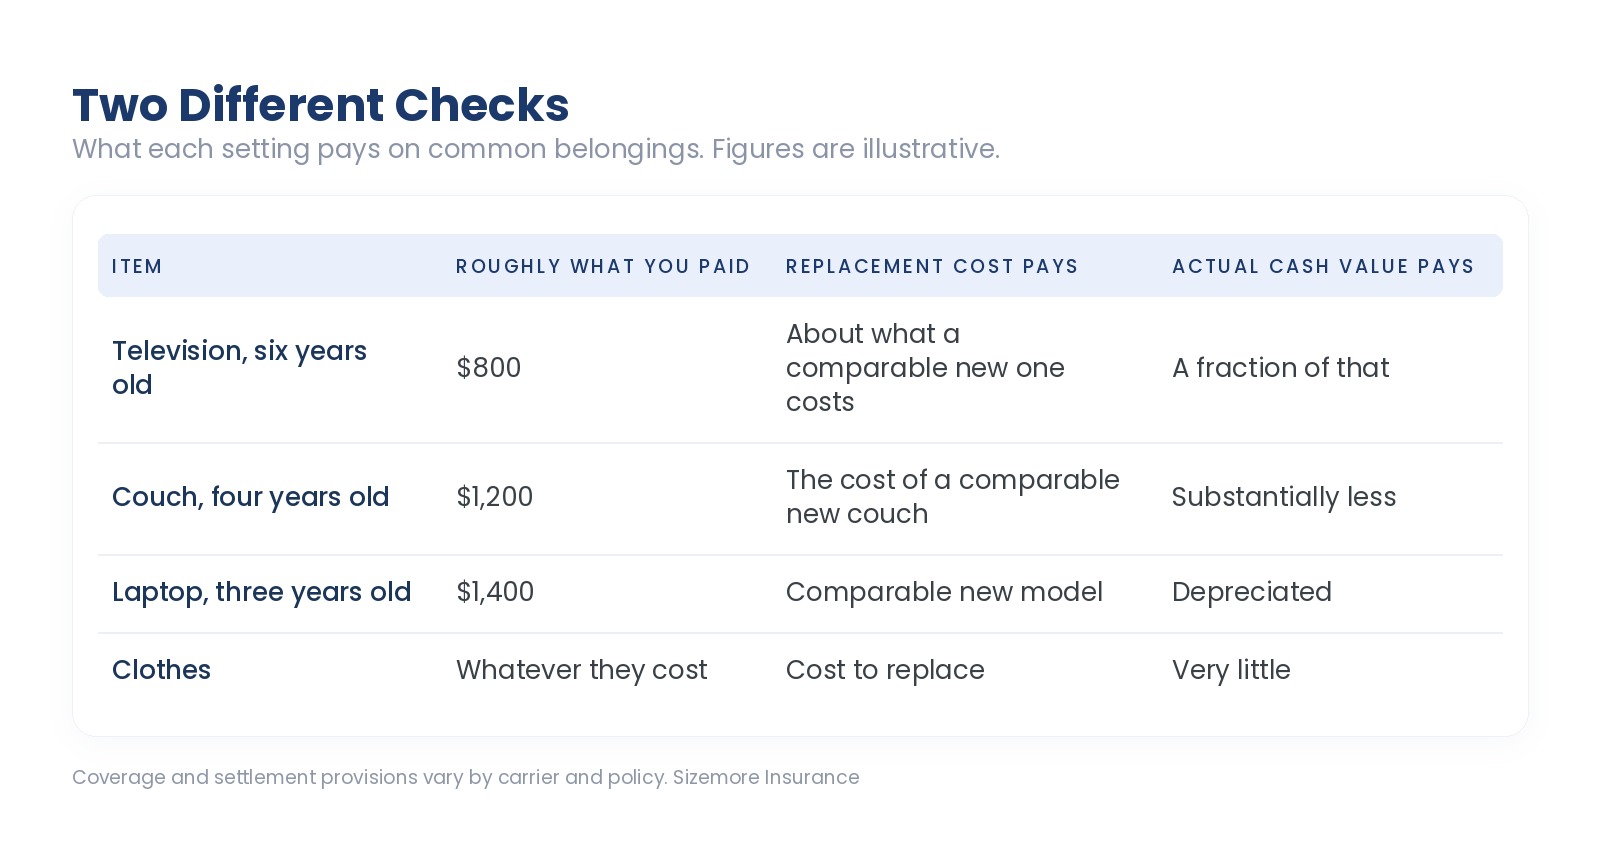
The takeaway: clothes and electronics depreciate fastest, and they make up much of what a renter owns.
Figures are illustrative. Coverage and settlement provisions vary by carrier and policy.
A homeowner’s largest claim is usually the structure. A renter’s entire claim is belongings, and belongings are one of the categories depreciation hits hardest.
After an apartment fire, you are replacing everything you own at today’s prices. Not at depreciated value from when you bought it.
Actual cash value on a full loss leaves a genuine gap between the check and what it costs to start over.
The premium difference is generally small. Replacement cost typically costs a little more per month and it can change the outcome substantially.
If you are choosing between a lower limit with replacement cost and a higher limit with actual cash value, take replacement cost.
Worth knowing because it surprises people.
Many policies pay the depreciated amount first, then pay the difference once you actually replace the item and show proof.
So you may need to buy the replacement and then submit receipts to collect the rest.
There is usually a time limit for doing that, frequently stated in the policy.
Which means keeping receipts matters during a claim, and it means understanding you may be out of pocket briefly.
Ask how your carrier handles it, because the process varies.
What is the difference?
Replacement cost pays what a new one costs today. Actual cash value pays the depreciated amount.
Which should I have?
Replacement cost, in most cases. The premium difference is generally small and the claim difference is not.
Why does it matter so much for renters?
Your entire claim is belongings, and belongings depreciate quickly.
Do I get the full amount right away?
Frequently the depreciated amount first, then the rest once you replace the item and show proof.
Is there a deadline to replace things?
Usually. Ask what yours is.
How do I know which I have?
It is on your declarations page. Ask us and we will check it in thirty seconds.
Sizemore Insurance is an independent insurance company founded in North Carolina in 1977, writing in both North Carolina and South Carolina. Send us your declarations page and we will tell you which one you have. Insurance made just for you.
Coverage, settlement provisions, and deadlines vary by carrier and policy and are subject to change. Figures are illustrative. Nothing here is a coverage determination. Review your own policy or talk to your advisor.