Insurance is one of the most common reasons an investment property closing slips, and almost never because the coverage was unavailable.
It slips because the request arrived incomplete and three days late.
Here is the checklist that prevents it, and the eight things that stall a funding.
The Checklist
- The property address, exactly.
- The vesting. Who is taking title. Individual, LLC, or trust, with the exact name from the state filing or the trust document.
- Occupancy at closing. Vacant, tenant occupied, mid-renovation, or short-term rental.
- Year built, square footage, and construction.
- Roof age and the last update to the roof, electrical, plumbing, and HVAC. These four decide insurability more than anything else on the list.
- The rent, actual or projected, plus the lease if there is one.
- The loan. Lender name, loan amount, program type, and the mortgagee clause from the lender’s own instructions.
- The lender’s insurance requirements, ideally the term sheet page that states them.
- The closing date.
- Prior claims, if any, on this property or on your other properties.
- Photographs, for anything vacant, renovating, or older.
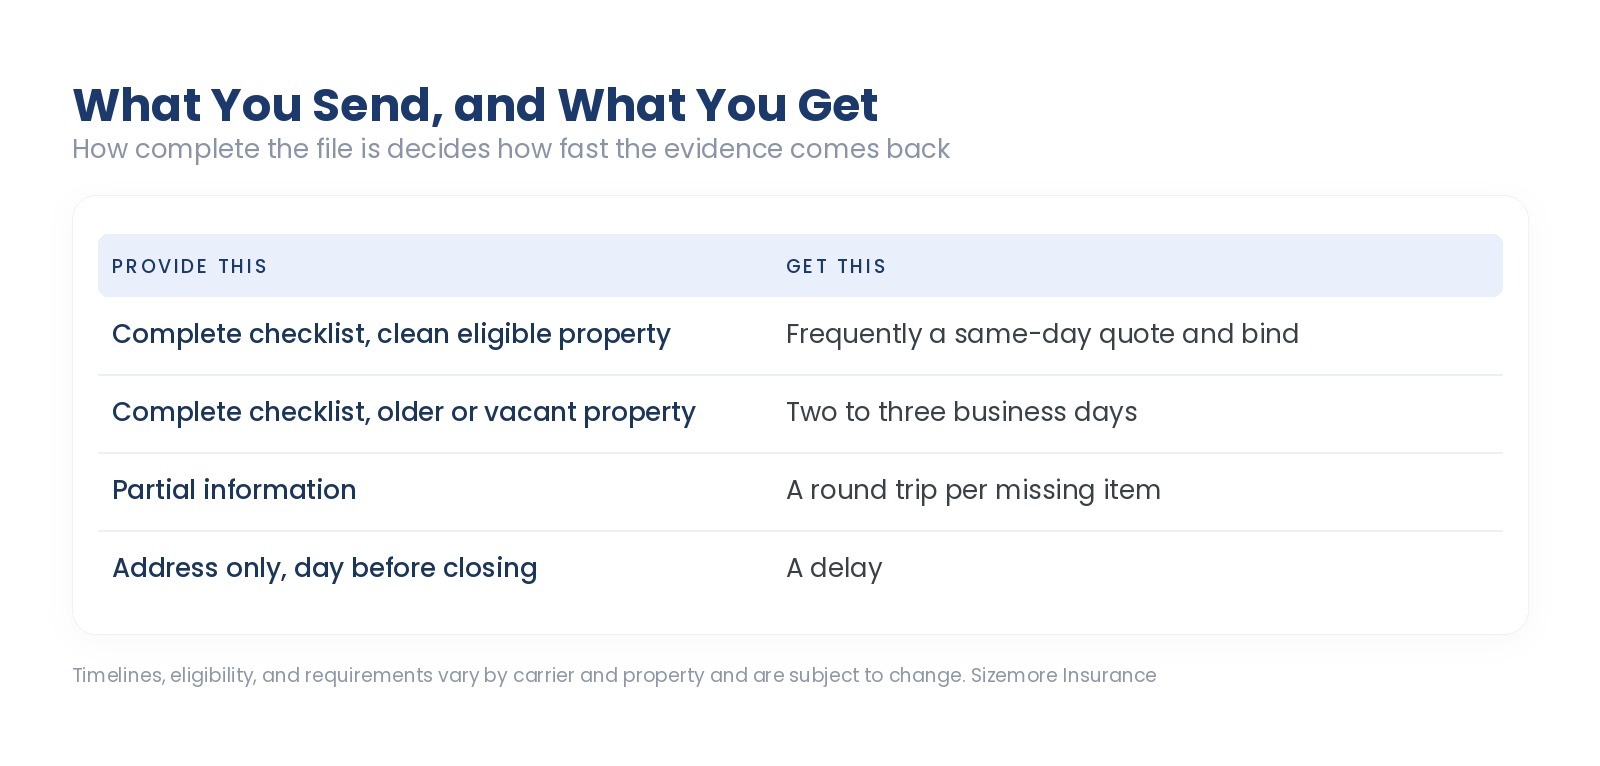
The takeaway: roof age and the systems update dates are the two items most often missing and the two that most determine whether a property is placeable at all.
Timelines, eligibility, and requirements vary by carrier and property and are subject to change.
The Eight Things That Stall a Funding
1. A wrong mortgagee clause. Frequently the most common of these and the easiest to fix. Take it from the lender’s instructions rather than a prior policy.
2. A named insured that does not match the vesting. The deed says LLC, the policy says the borrower.
3. A late vesting change. The decision to take title in an entity gets made the week of closing, and the policy has to be rewritten.
4. An effective date after closing. Coverage has to be in force when the loan funds.
5. A late flood zone determination. If the property is in a mapped zone, a flood policy has to be issued, and finding out three days out compresses everything.
6. An insurability surprise. A twenty-five-year-old roof, a fuse panel, knob and tube wiring, or polybutylene plumbing. Those narrow the market and take time to work.
7. A deductible above the lender’s maximum, chosen to lower the premium.
8. Actual cash value instead of replacement cost, which is a basic form policy failing a replacement cost requirement.
Every one of those is preventable with a week of notice and a complete file.
For Loan Officers
If you are sending a borrower here, the fastest path is to forward this checklist with the term sheet page that states your insurance requirements.
We will confirm the same day whether the property is placeable, flag any insurability issue while there is still time to solve it, and issue evidence of insurance with your mortgagee clause exactly as you provided it.
The two things that help most on your side: get the vesting locked before the file comes to us, and order the flood determination early.
Where This Gets Complicated
A property that is not eligible is better known on day one than day nine. Older systems and roof age are the usual reasons, and sometimes the answer is a repair before closing.
Multiple properties closing together need schedules and consistent documentation.
A renovation loan needs builders risk rather than a landlord policy, which has its own article.
Escrow setup affects who receives the bill and who watches the renewal.
A last-minute deductible or limit change from the lender means reissuing documents.
A short closing window on a hard-to-place property is the one combination that genuinely cannot always be solved fast.
Common Questions
How fast can you quote an investment property?
Frequently same day on a clean, eligible property with complete information. Two to three business days on older, vacant, or renovating property.
What do you need first?
Address, vesting, occupancy, roof and systems ages, the loan details, and the lender’s requirements.
What most often causes a delay?
A wrong mortgagee clause, a named insured mismatch, or an insurability surprise found late.
Can you do same-day?
Where the property is eligible and the information is complete, frequently yes.
What if the roof is old?
It narrows the market and it is workable. Tell us early rather than at closing.
Can I send this to my loan officer?
Yes. That is who half of this article is written for.
The Bottom Line
- Send the complete checklist, not the address alone.
- Lock the vesting before we bind.
- Include roof and systems ages, because they decide eligibility.
- Take the mortgagee clause from the lender’s instructions.
- Order the flood determination early.
- Call a week out rather than three days out, because everything on this list is solvable with time.
Sizemore Insurance is an independent insurance company founded in North Carolina in 1977, writing in both North Carolina and South Carolina. Send the checklist and we will tell you the same day whether it is placeable and what it takes. Insurance made just for you.
Timelines, eligibility, requirements, and processes vary by carrier, lender, and property and are subject to change. Nothing here is a coverage determination. Review your own situation with your advisor.