

Two houses a block apart on the same island can be in different flood zones, and the difference changes three things at once: what the flood policy costs, how the house is required to be built, and what the coverage actually pays for.
Most owners know their zone as a letter on a form the lender needed. It is worth understanding what the letter means.
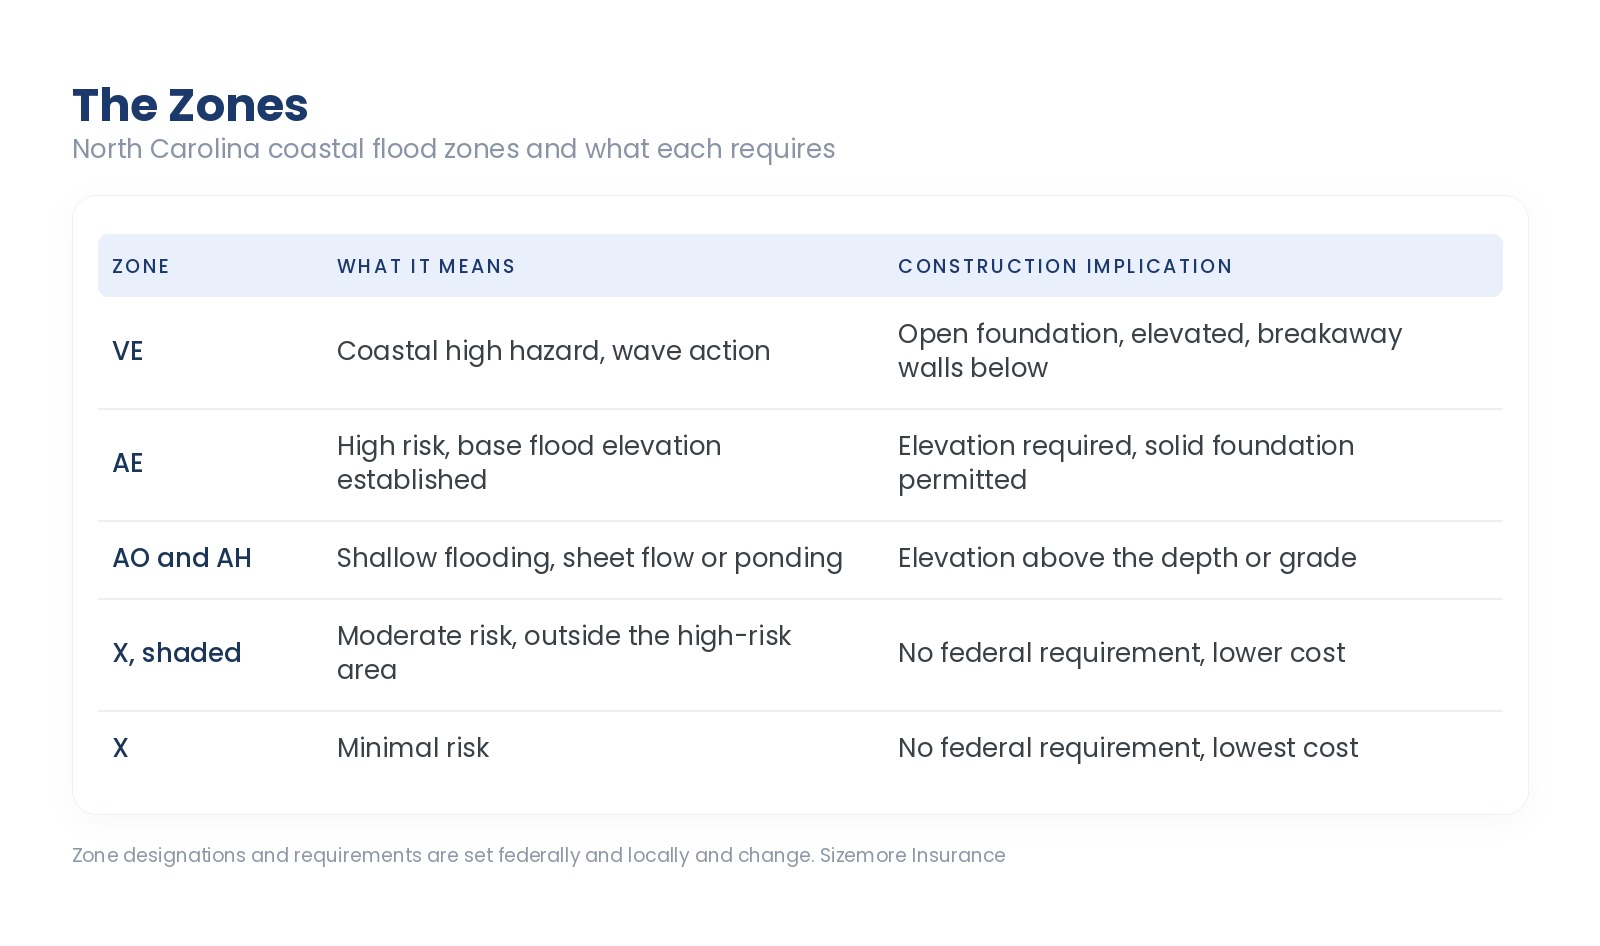
The takeaway: VE and AE are both high risk, and VE is where wave action changes how the house must be built and how it is insured. X is where many owners skip coverage, and homes in those zones still flood.
Zone designations, requirements, and program terms are set federally and by local jurisdictions and change. Confirm with your local floodplain administrator.
VE zones are the coastal high hazard areas where waves are expected during a base flood event. Construction requirements there are considerably more demanding.
Open foundation. The house sits on pilings or columns so water and waves pass underneath rather than pushing against a solid wall.
Elevation to the lowest horizontal structural member. The measurement is to the bottom of the lowest supporting beam, not to the floor.
Breakaway walls below the elevation. Any enclosure underneath has to be built to fail under wave load without taking the structure with it.
Limited use of the space below. Parking, access, and storage. Not living space. This is the requirement homeowners most often violate over time, by finishing a ground level for use as a rec room or bedroom.
That last one matters for coverage as well as for permits. Finishing a below-elevation enclosure can jeopardize your flood coverage and can create a violation that follows the property.
Very little, and it is one of the most consequential things a coastal homeowner can learn about flood insurance.
In an elevated home, the enclosed area below the base flood elevation receives limited building coverage, generally confined to essential building elements and certain equipment. Contents stored down there are largely uncovered.
The garage refrigerator, the golf cart, the beach furniture, the tools, the surfboards. Almost none of it is covered by a flood policy.
Owners find this out after the fact, and they are frequently the same owners who added coverage carefully and did everything right on the floors above.
Your elevation certificate is worth having. It documents the structure's elevation relative to the base flood elevation, and under current federal rating methodology property-specific characteristics drive the premium. On a coastal home it is frequently worth the cost of obtaining one.
Zones get remapped. A house that was X can become AE. When maps change, there are provisions that can preserve favorable rating for owners who had coverage in place beforehand, which is one more argument for buying before you are required to.
Being outside a high-risk zone is not being outside risk. Homes in moderate and minimal risk zones flood, and on the mainland side of these counties that is a common story.
The federal caps do not move with the zone. Residential building coverage caps at $250,000 and contents at $100,000 regardless of zone. On any coastal house worth more than that to rebuild, excess flood is where the actual coverage lives.
Substantial damage rules apply at rebuild. Damage exceeding a defined percentage of value can require the structure to meet current requirements, including elevation. Ordinance or law coverage on the homeowners side addresses part of that and increased cost of compliance under the flood policy addresses another part. Neither covers all of it.
The 30-day waiting period rules out buying late. Flood generally cannot be bought once a storm has a name, with narrow exceptions tied to loan closings.
What is the difference between an AE and a VE flood zone?
Both are high risk. VE adds expected wave action, which requires an open elevated foundation and breakaway walls, and it prices higher.
Am I required to buy flood insurance?
If you have a federally regulated loan and the house is in a high-risk zone, yes. Outside those zones it is optional and usually inexpensive.
Is my garage covered under a flood policy?
In an elevated home, coverage for the enclosed area below the flood elevation is limited and contents stored there are largely uncovered.
What is an elevation certificate and do I need one?
A document recording your structure's elevation relative to the base flood elevation. On a coastal home it is frequently worth obtaining because property-specific characteristics drive the rate.
My zone changed. What happens to my rate?
It depends on the change and on whether you had coverage before the remapping. Provisions exist that can preserve favorable treatment, which is another reason to buy early.
Can I finish the space under my elevated house?
In a VE zone that is generally restricted to parking, access, and storage. Converting it to living space can create a permit violation and jeopardize your flood coverage.
We have been an independent insurance company in North Carolina since 1977. Send us the address and we will pull the zone, look at the elevation, and tell you what the flood layer should look like. Insurance made just for you.
Zone designations, construction requirements, program limits, and rating methodology are set federally and locally and are subject to change. Review your own policy or talk to your advisor.